
Doom. Gloom. Another headline telling us how bad the property market is.
Read enough of them and you would wonder why any estate agent bothers opening the office.
Yet homes are still selling. Buyers are still buying. People are still moving.
Dont get me wrong, it’s tough out there … but so many estate agents are acting like its end of the world. …. the stats though tell a different story
So what are the headlines missing?
In this week’s UK Property Market Stats Show, Dan Marsden and I get underneath the noise and into the numbers and as you might expect, the UK property market statistics very quickly turn into many hard hitting home truths for estate agents when we talk about overvaluing, cheap fees & why agents leave price reductions too late & why getting the listing is pointless if the strategy afterwards does not actually help the homeowner move.
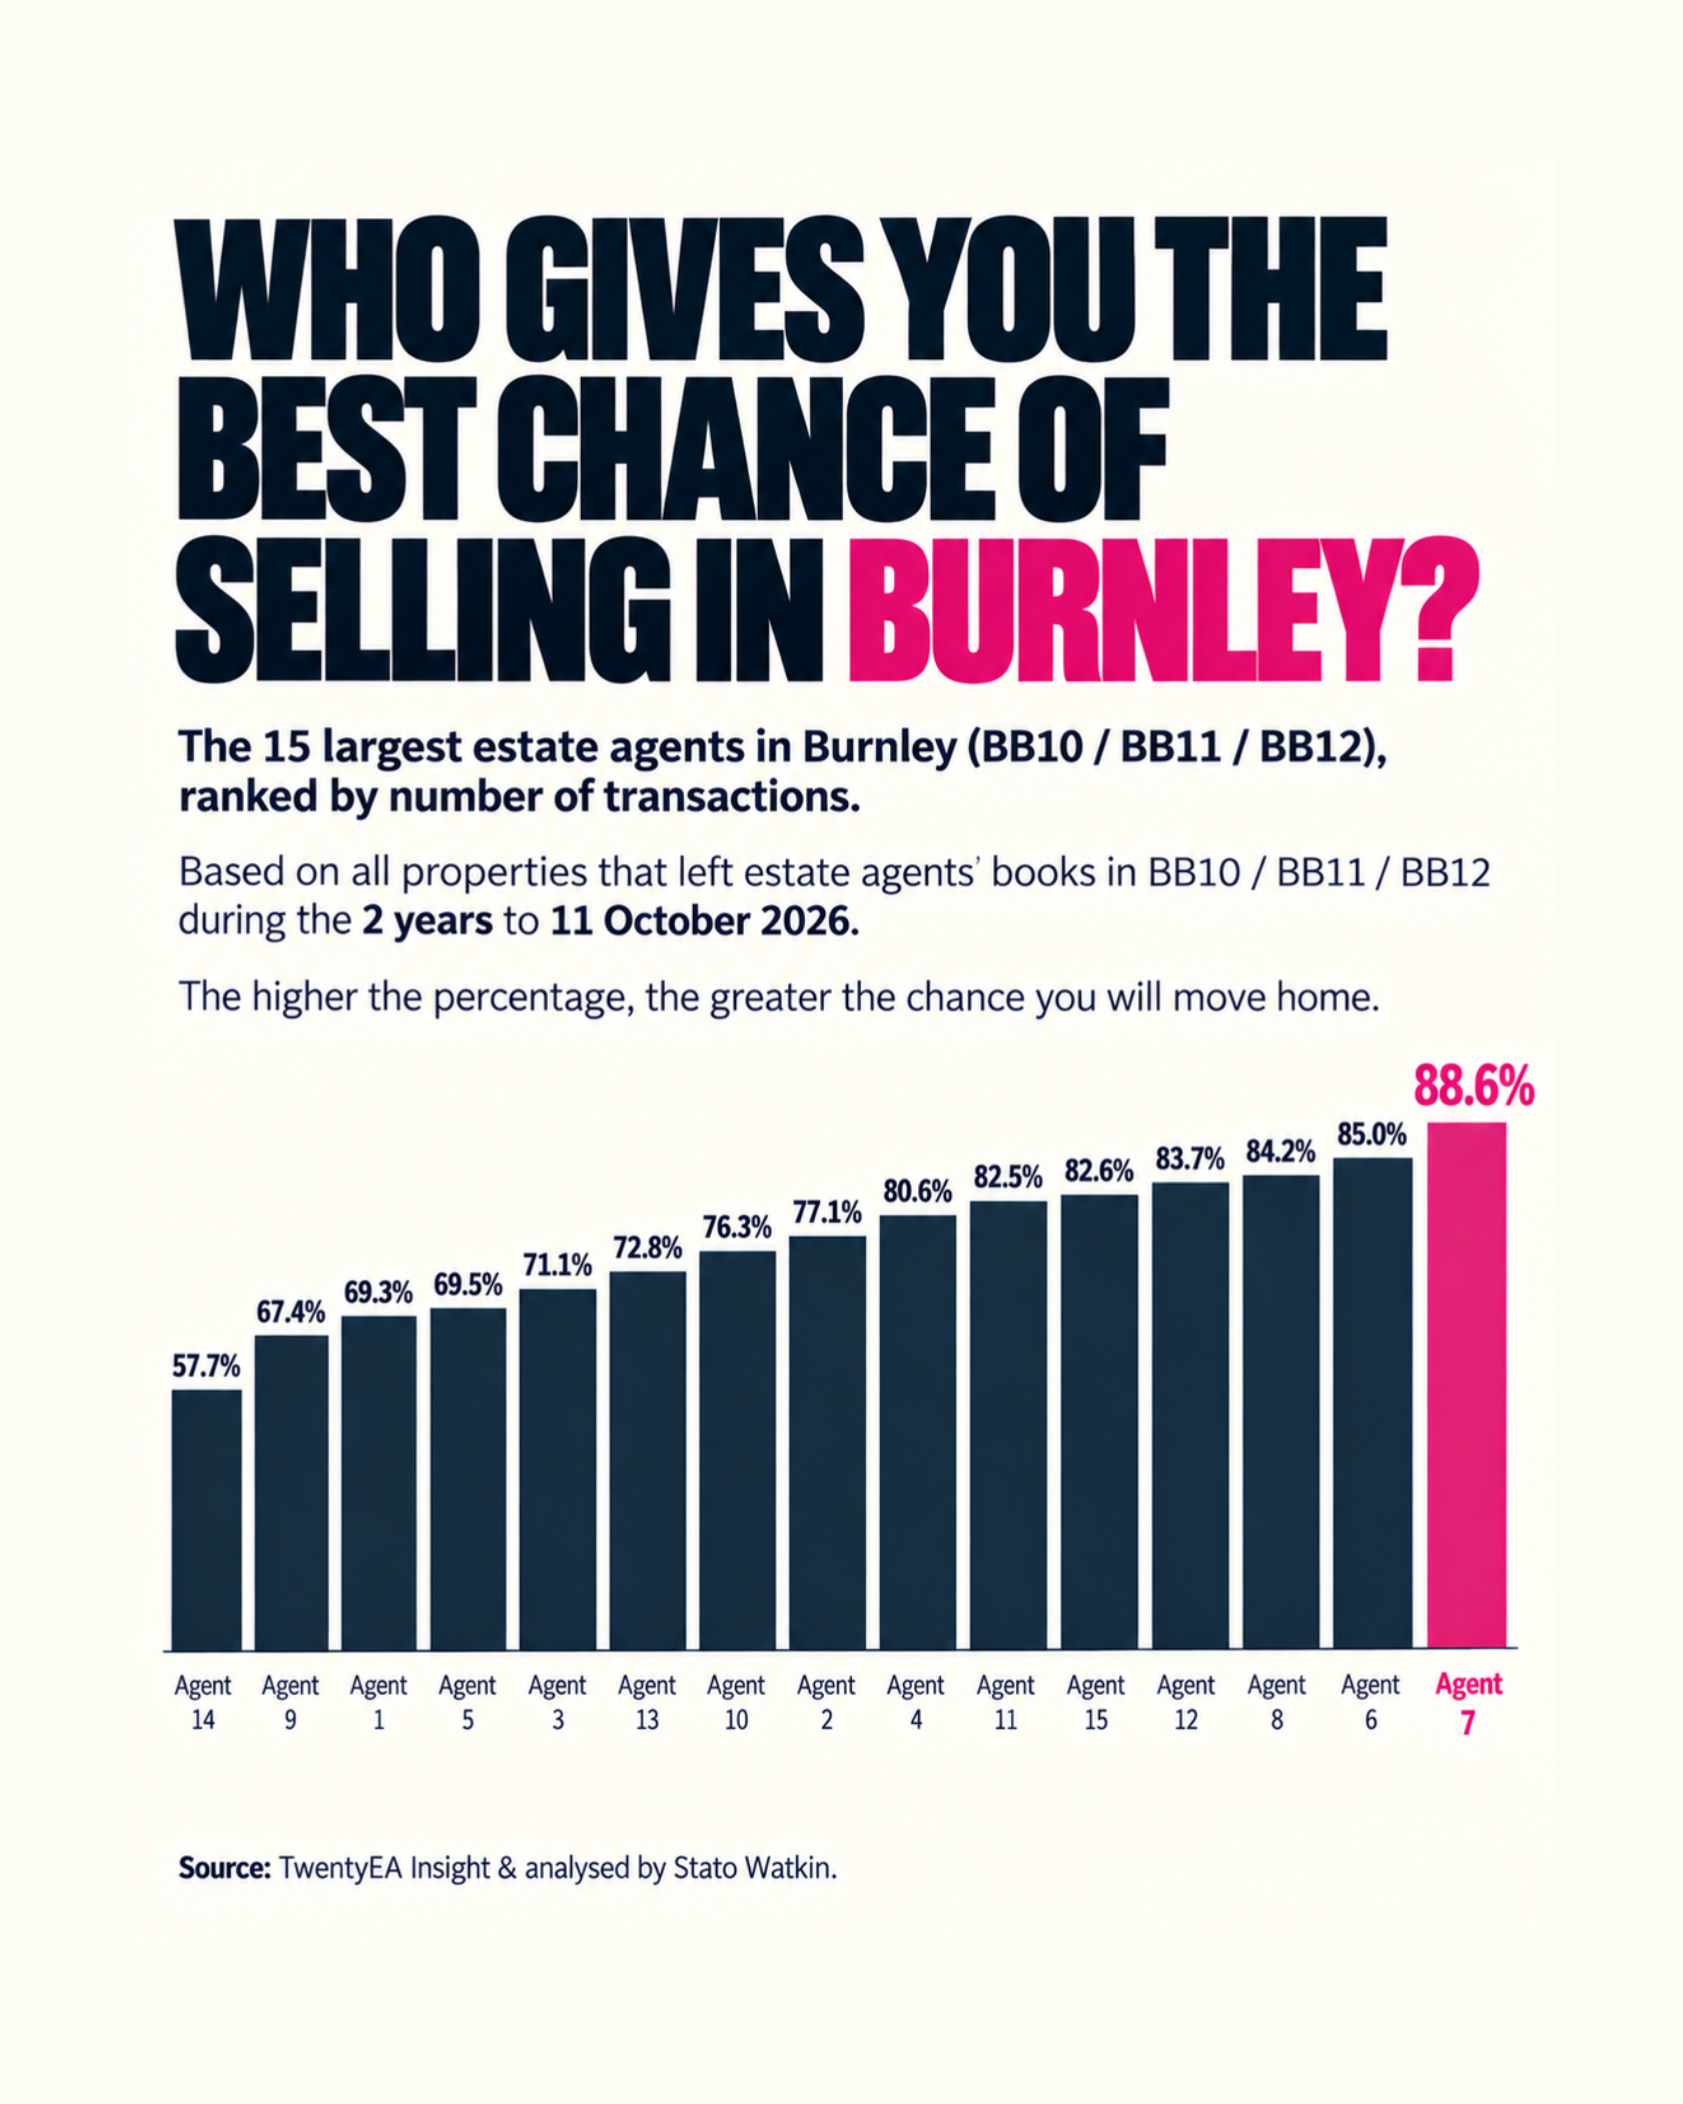
In the second part of the show, we head to Burnley and put the local Burnley estate agents under the microscope. Not simply who lists the most homes, but who actually gives homeowners the strongest chance of moving, who achieves the better prices and who appears to be gaining ground locally. If you are an estate agent anywhere in the UK, the way we analyse Burnley might give you a few ideas about how you could prove your own value too.
🟩 Listings
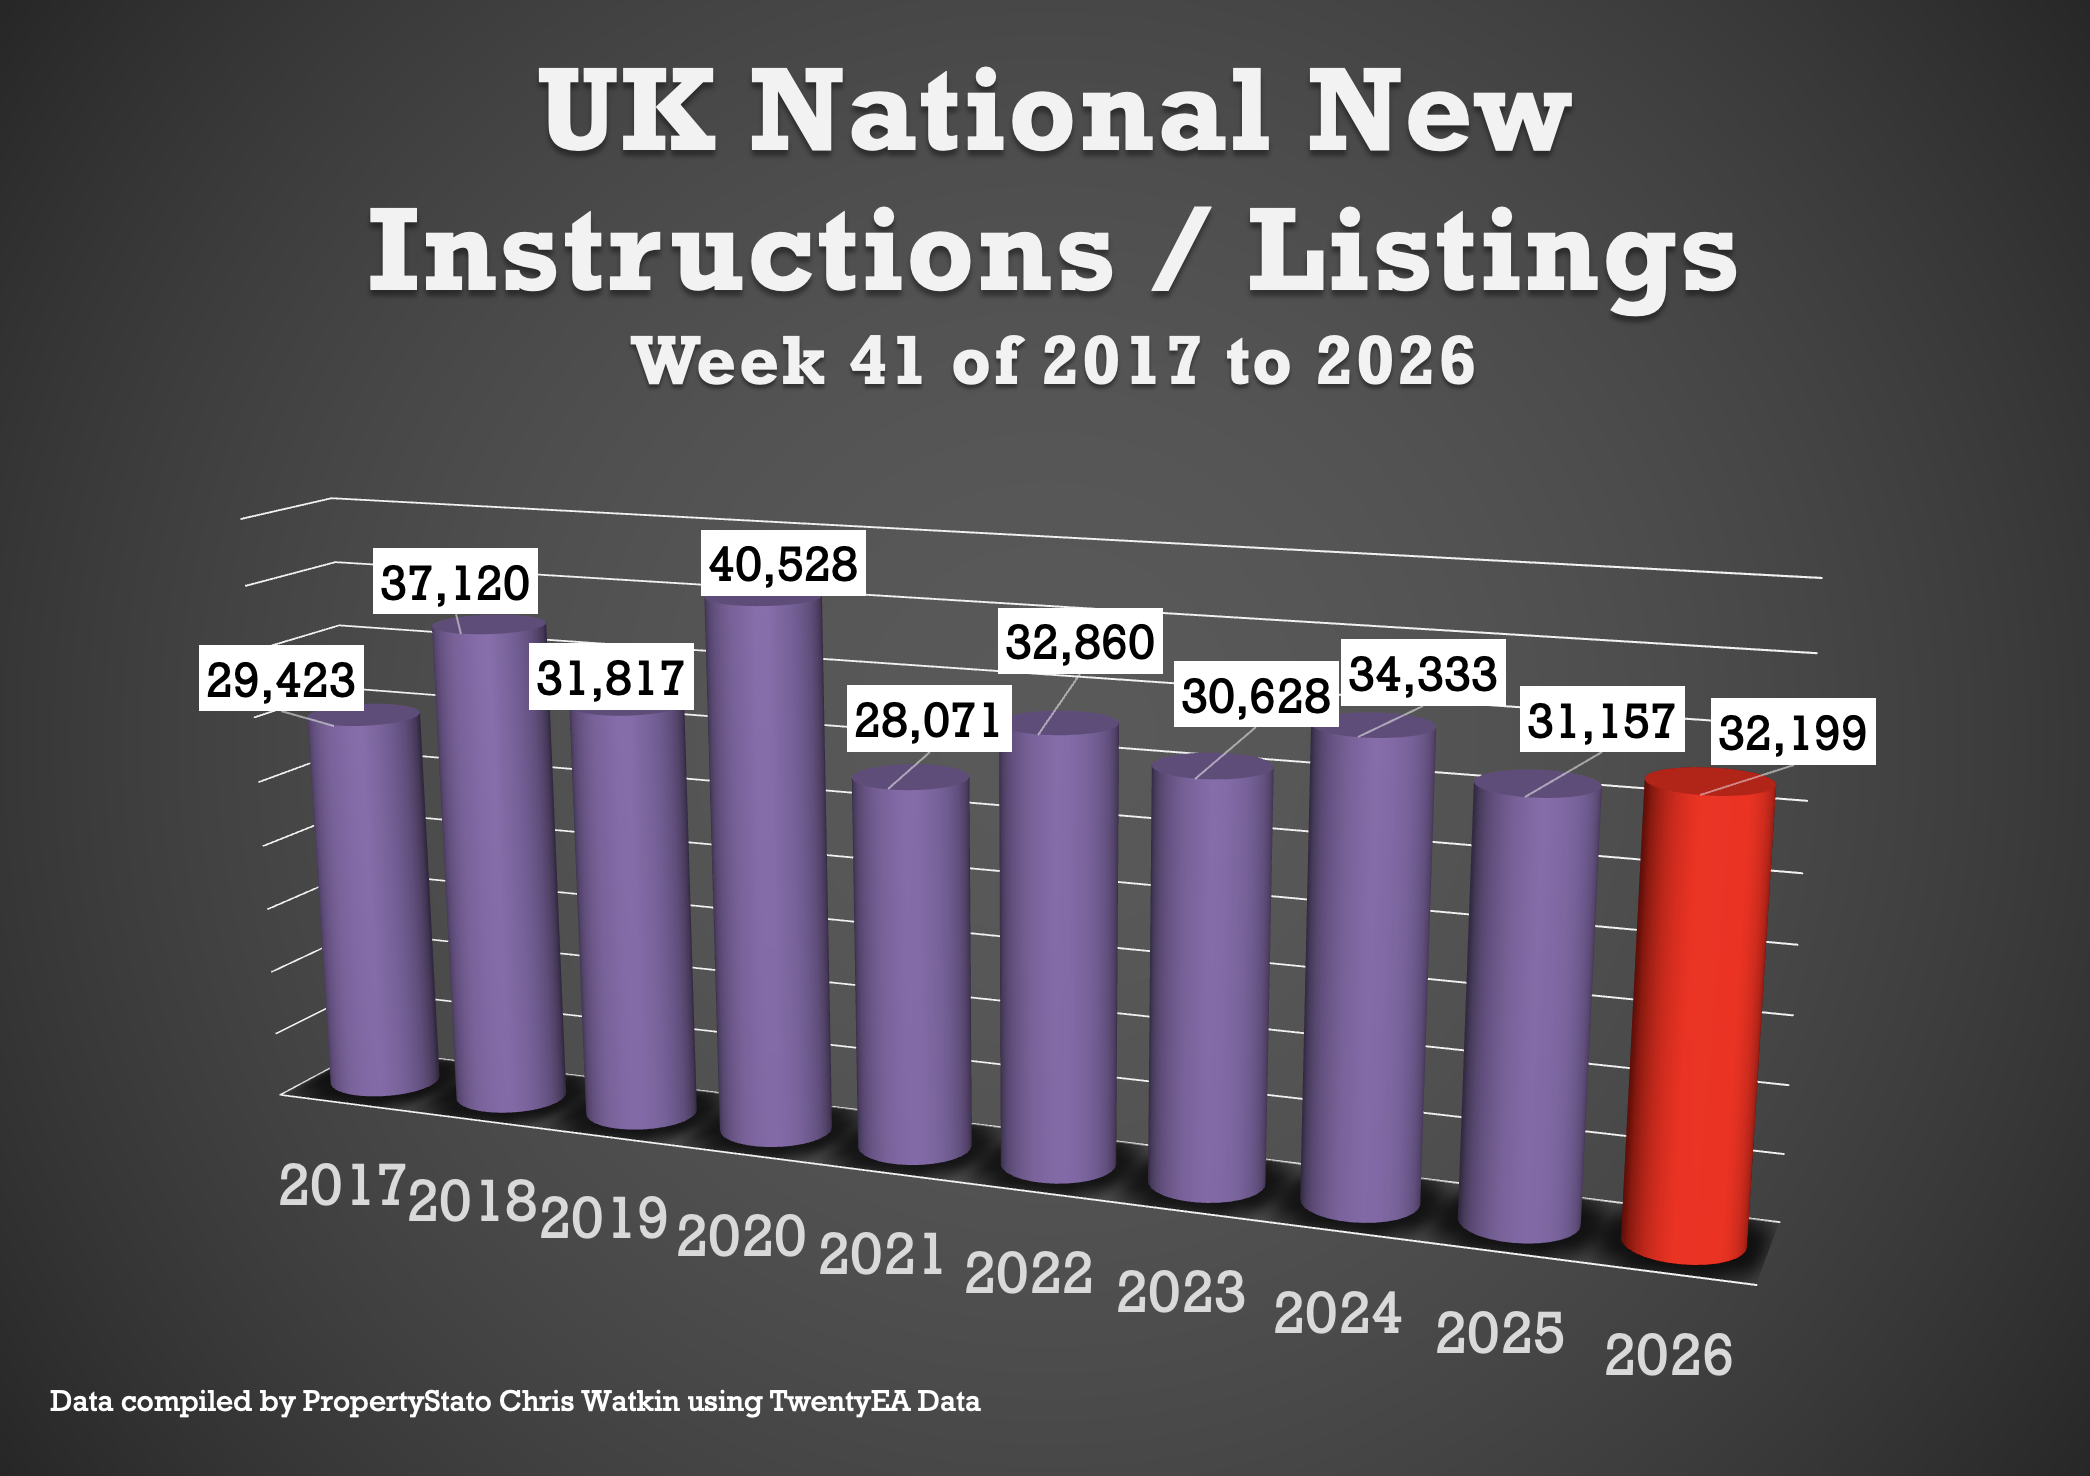
Week 41 ..
32.2k new listings this week, (33k last week).
Weekly 2026 average : 35.9k.
10 year week 40 average : 32.8k
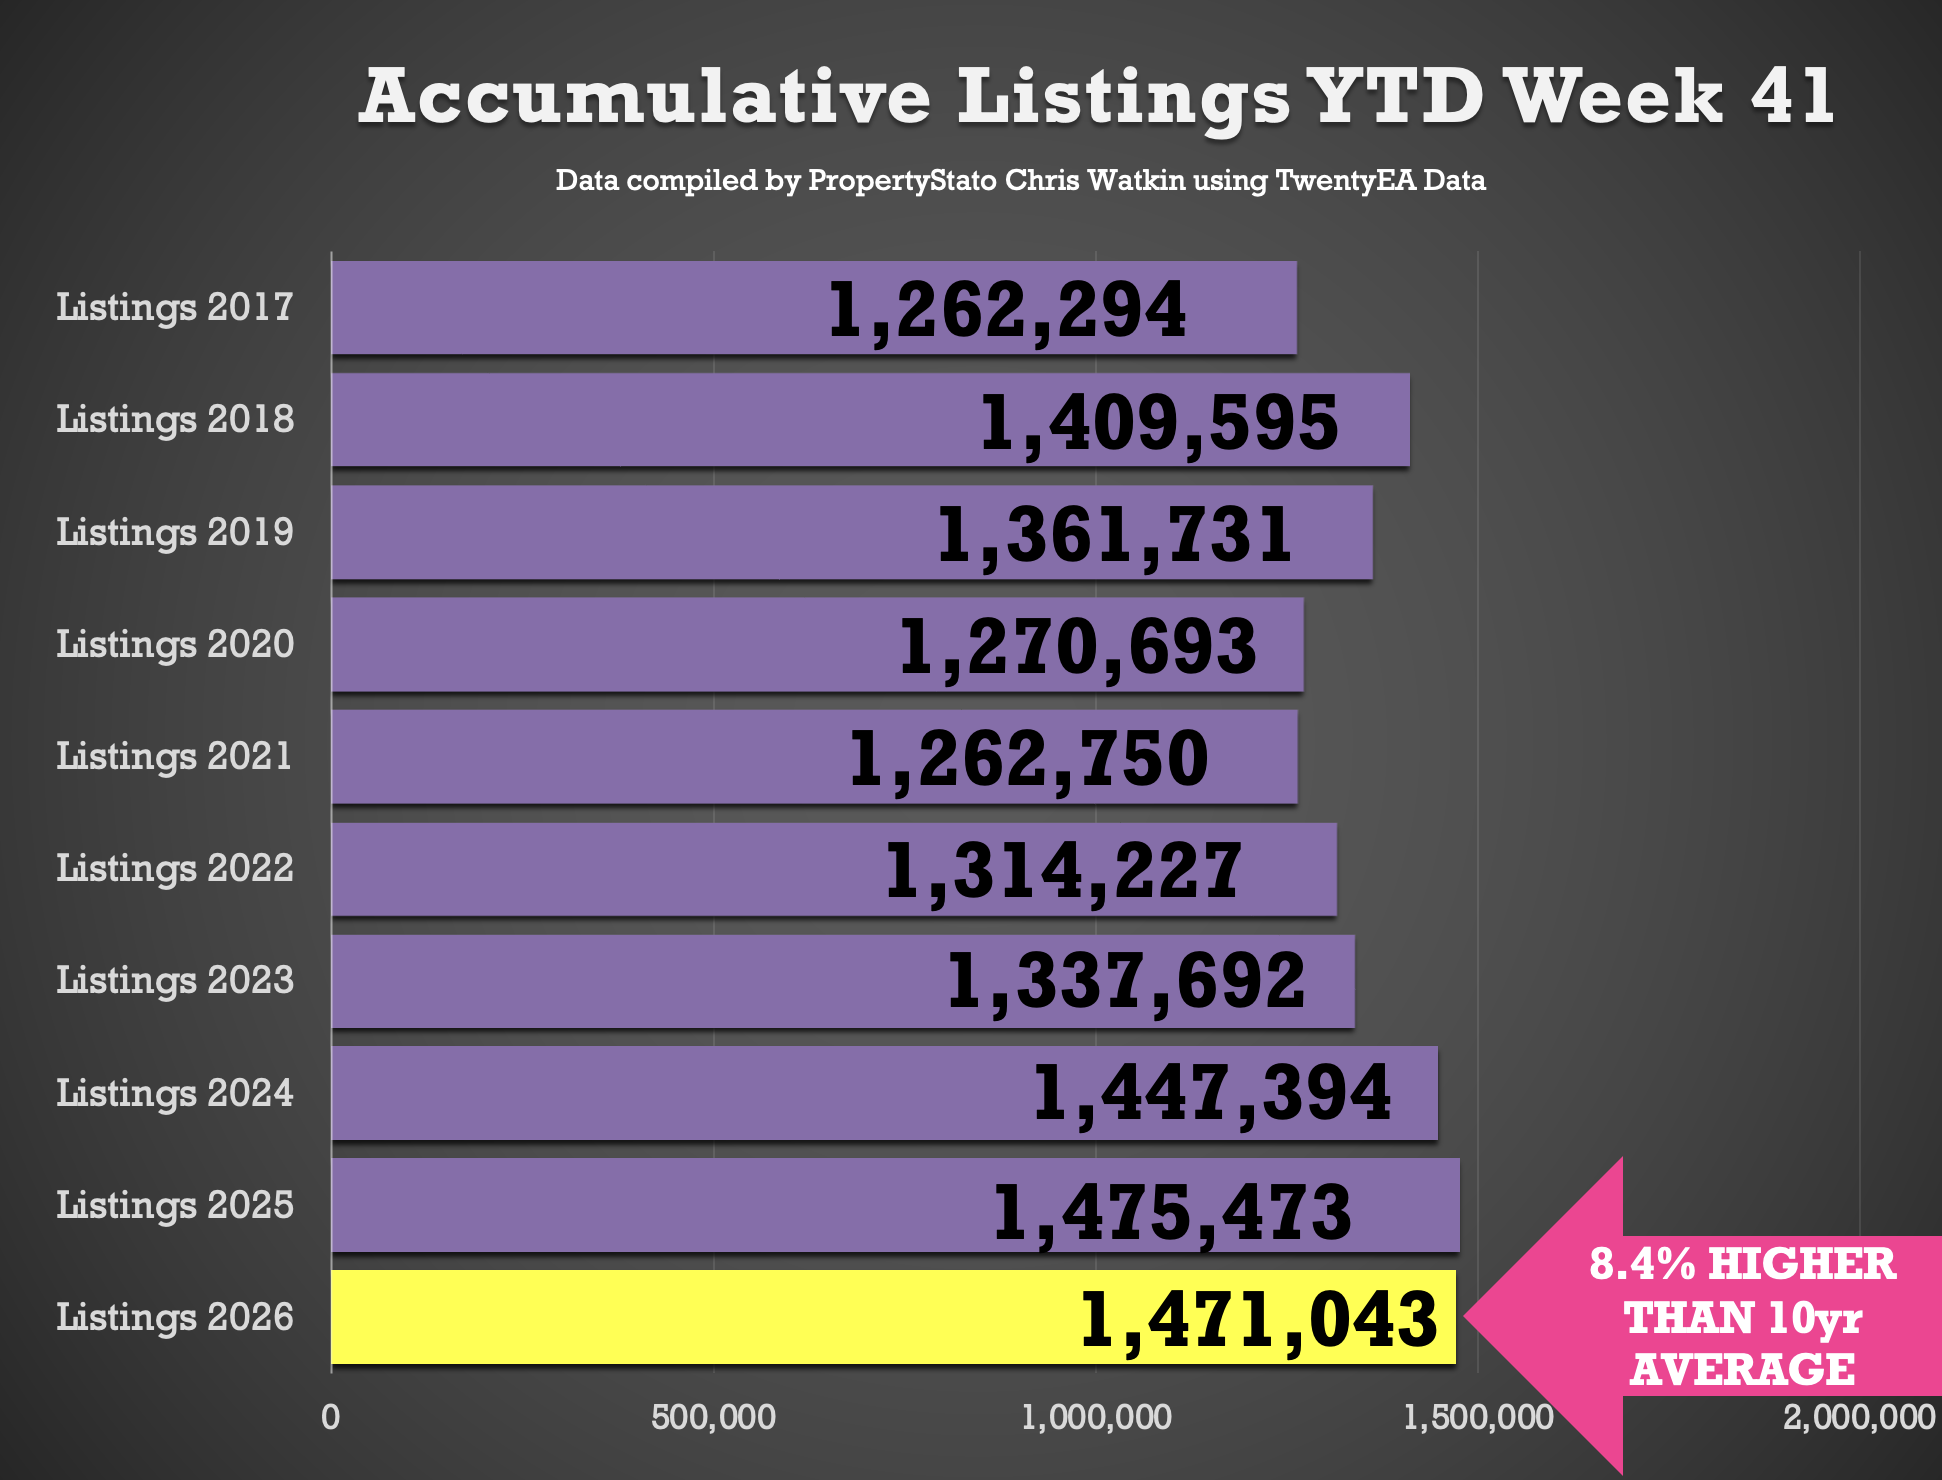
Year to Date
1.471m new listings YTD, which is …
0.3% below 2025 YTD (1.475m)
1.6% higher of 2024 YTD (1.447m)
9.4% higher of 2023 YTD (1.338m)
9.4% higher than the 2017–19 average YTD (1.336m).
8.4% higher than last decade YTD average – 1.361m.
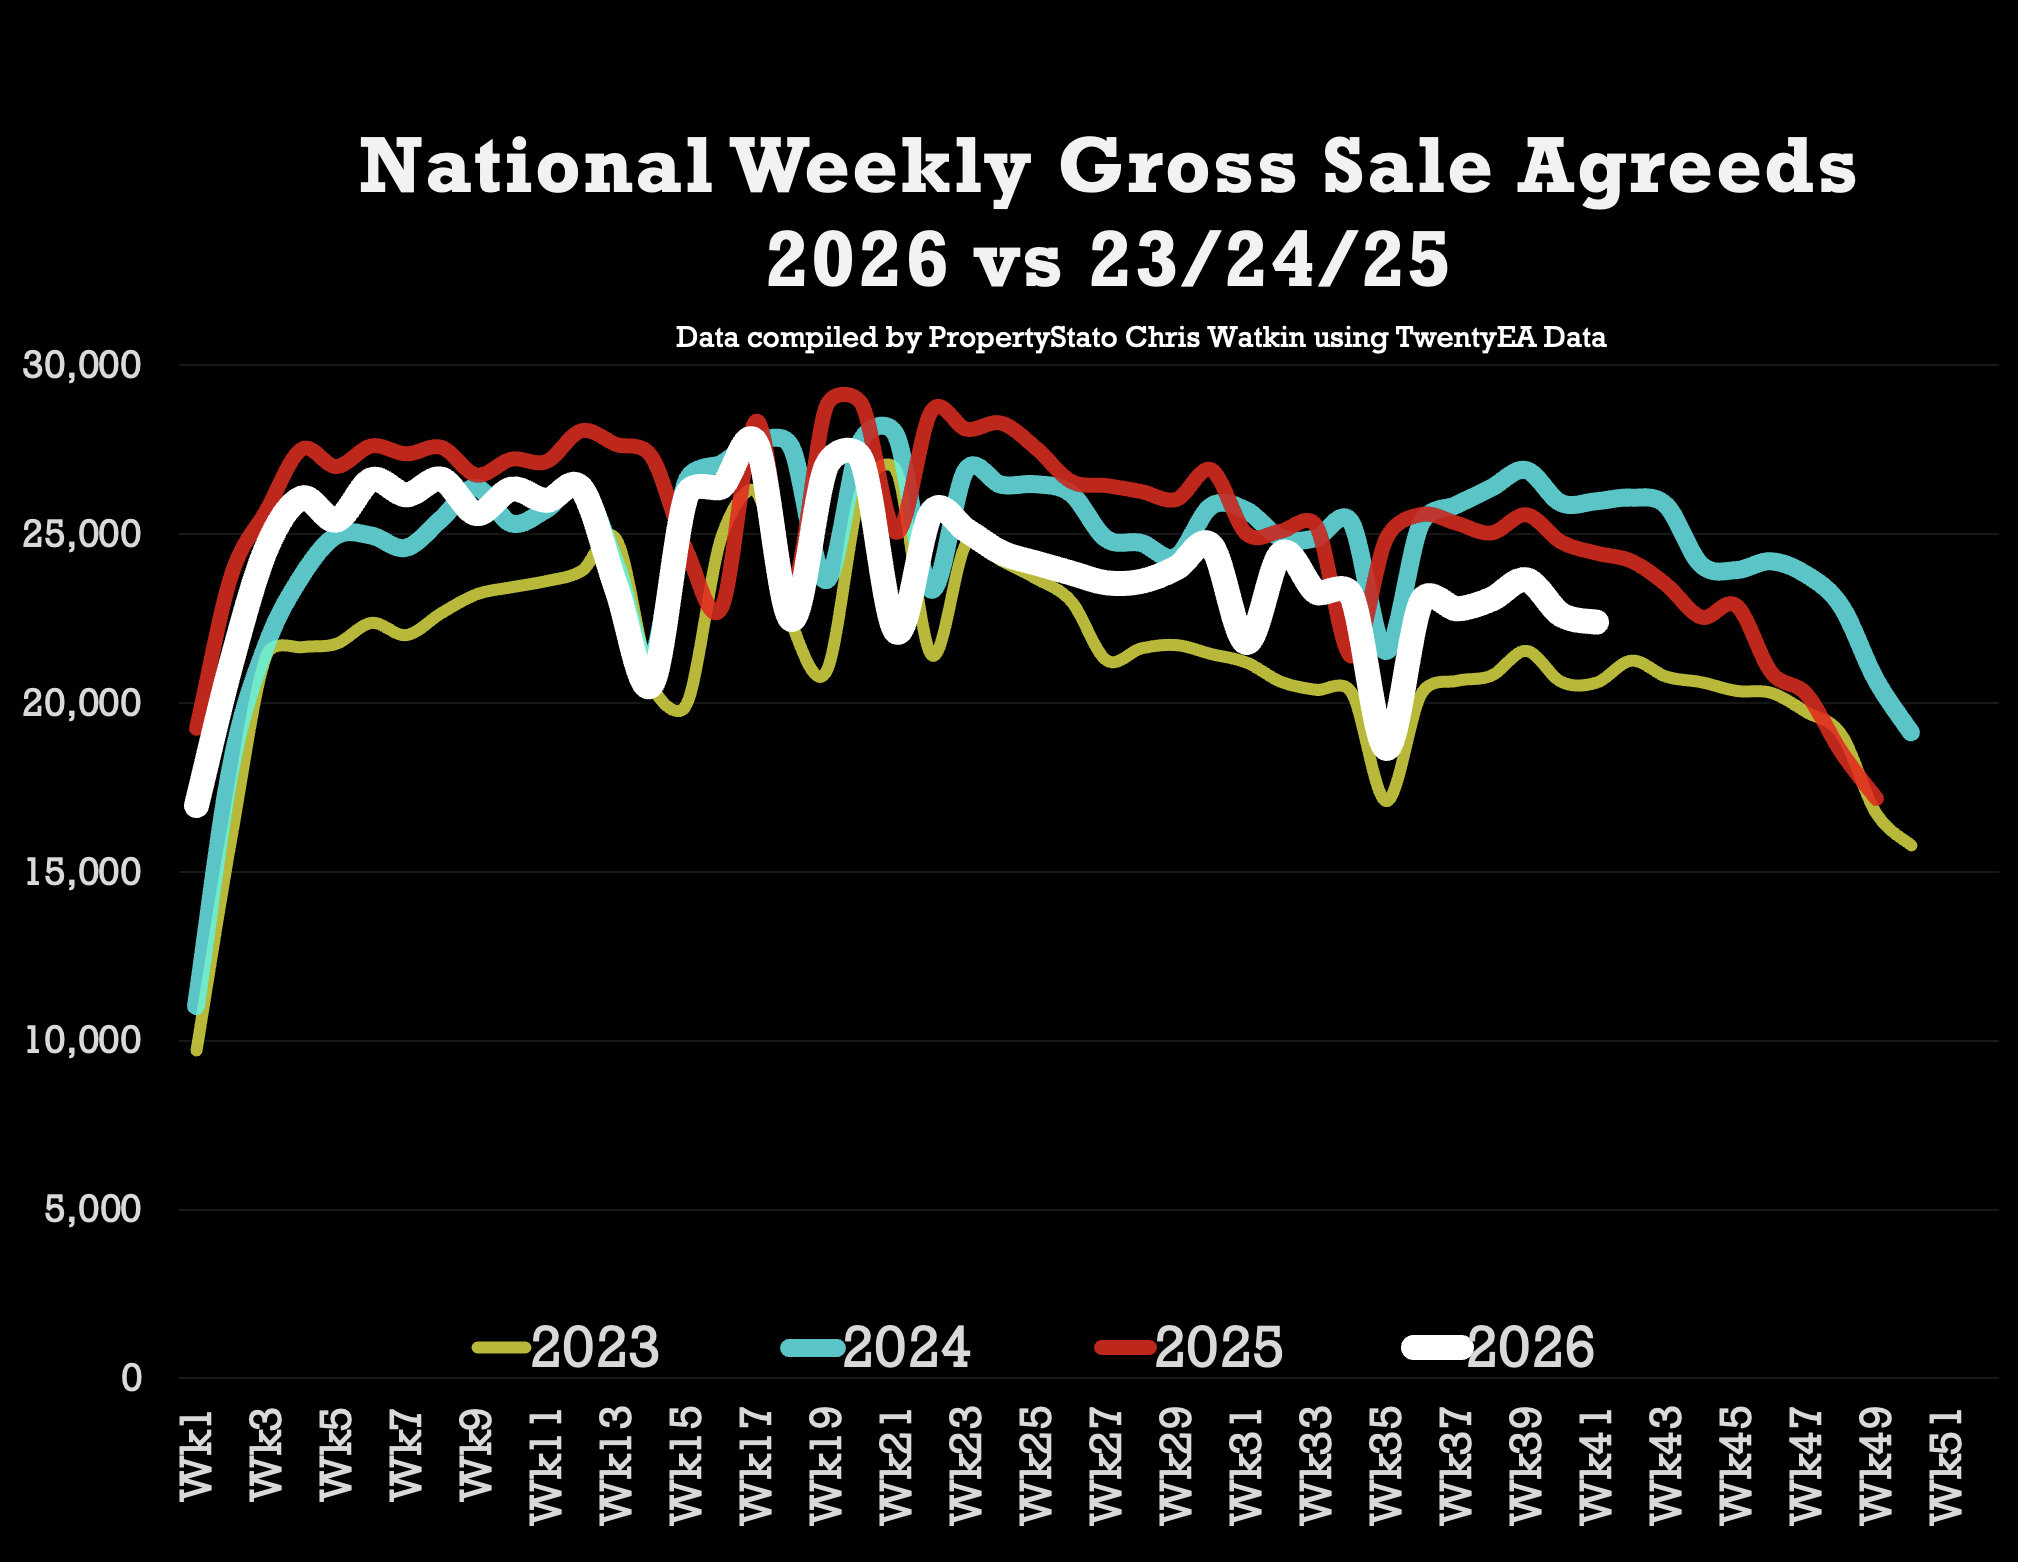
🟩 UK Gross Resi Sales
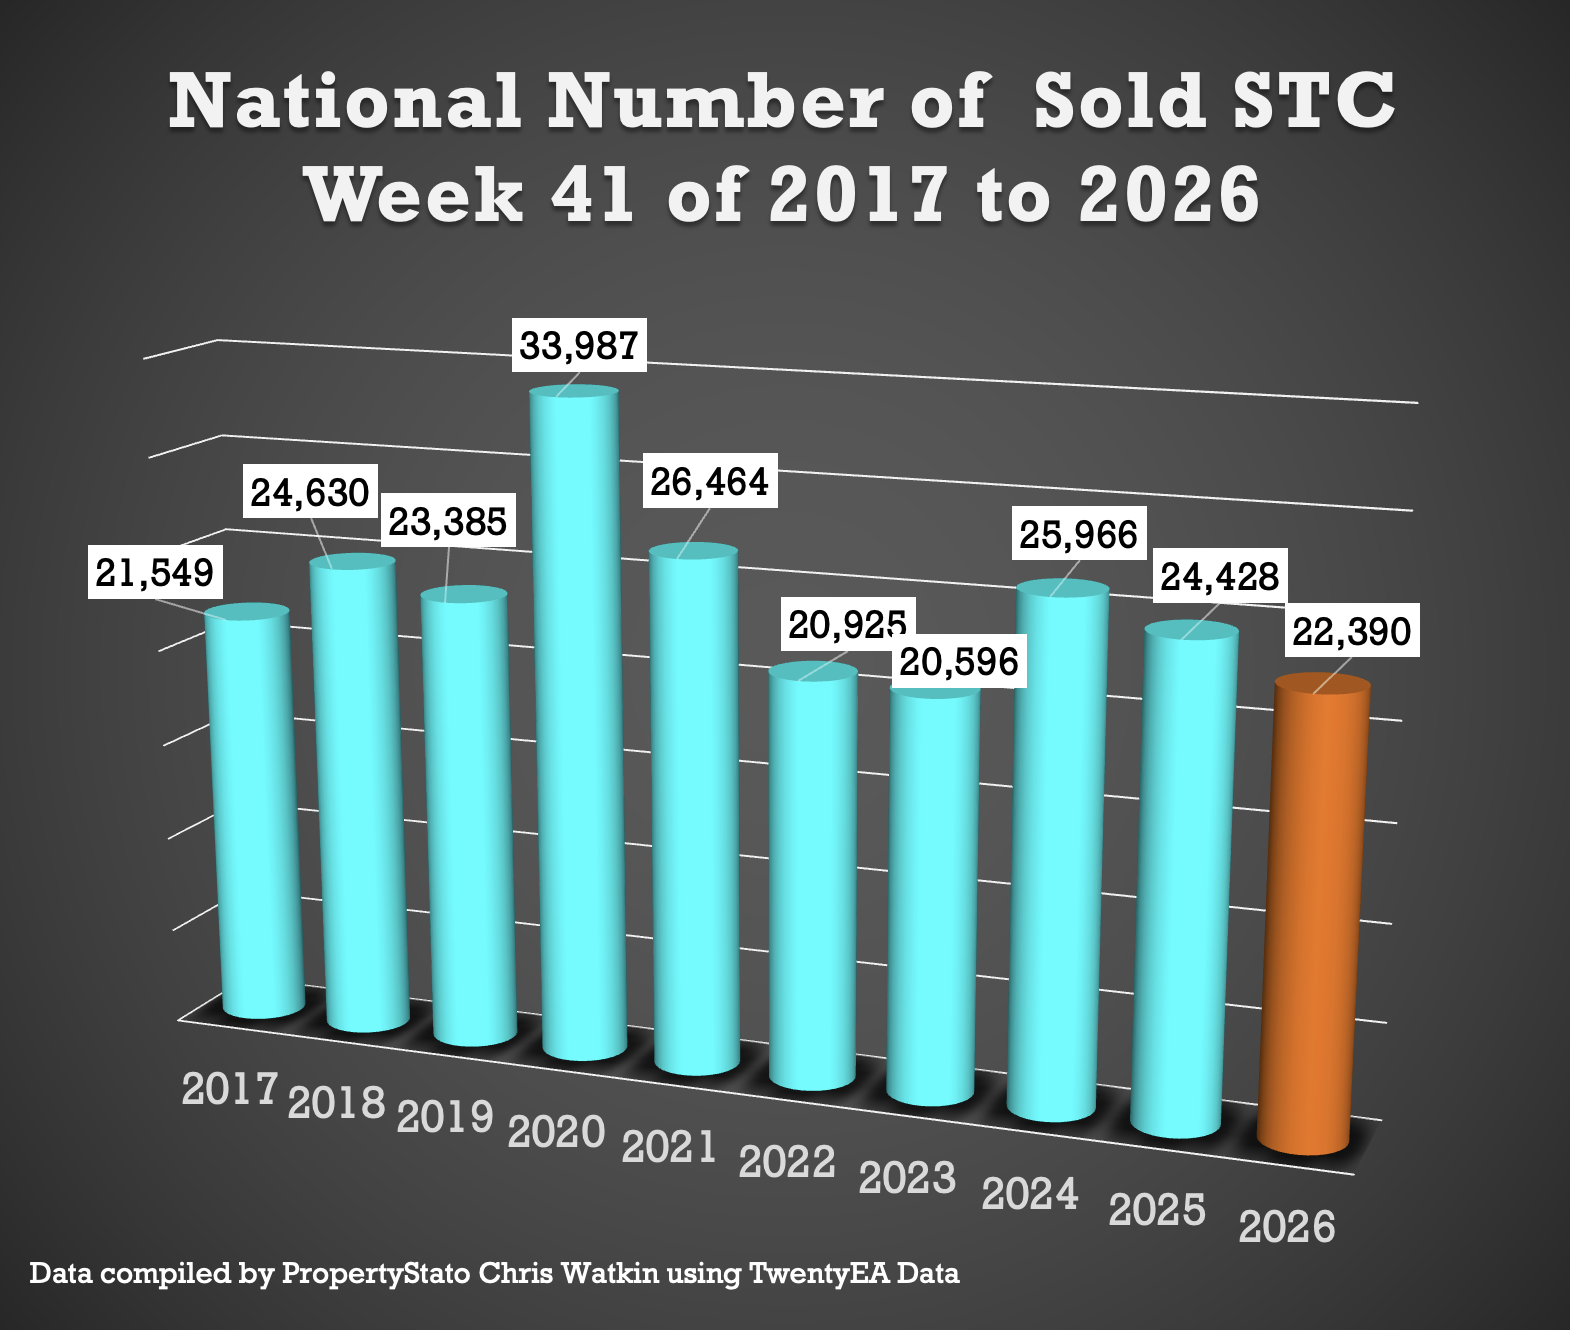
Week 41 ..
22.4k homes sold stc this week 40 (22.6k last week)
10 year week 41 average : 24.4k
2026 weekly average : 24.1k.
Year to Date for house sales
989k UK homes sold stc YTD, which is …
7.5% lower than 2025 YTD (1.068m)
3% lower to 2024 YTD (1.019m)
10.9% higher than 2023 YTD (891k)
4.5% higher above pre Covid 2017-19 years (946k).
1.5% lower than the last decade YTD average (1.004m).
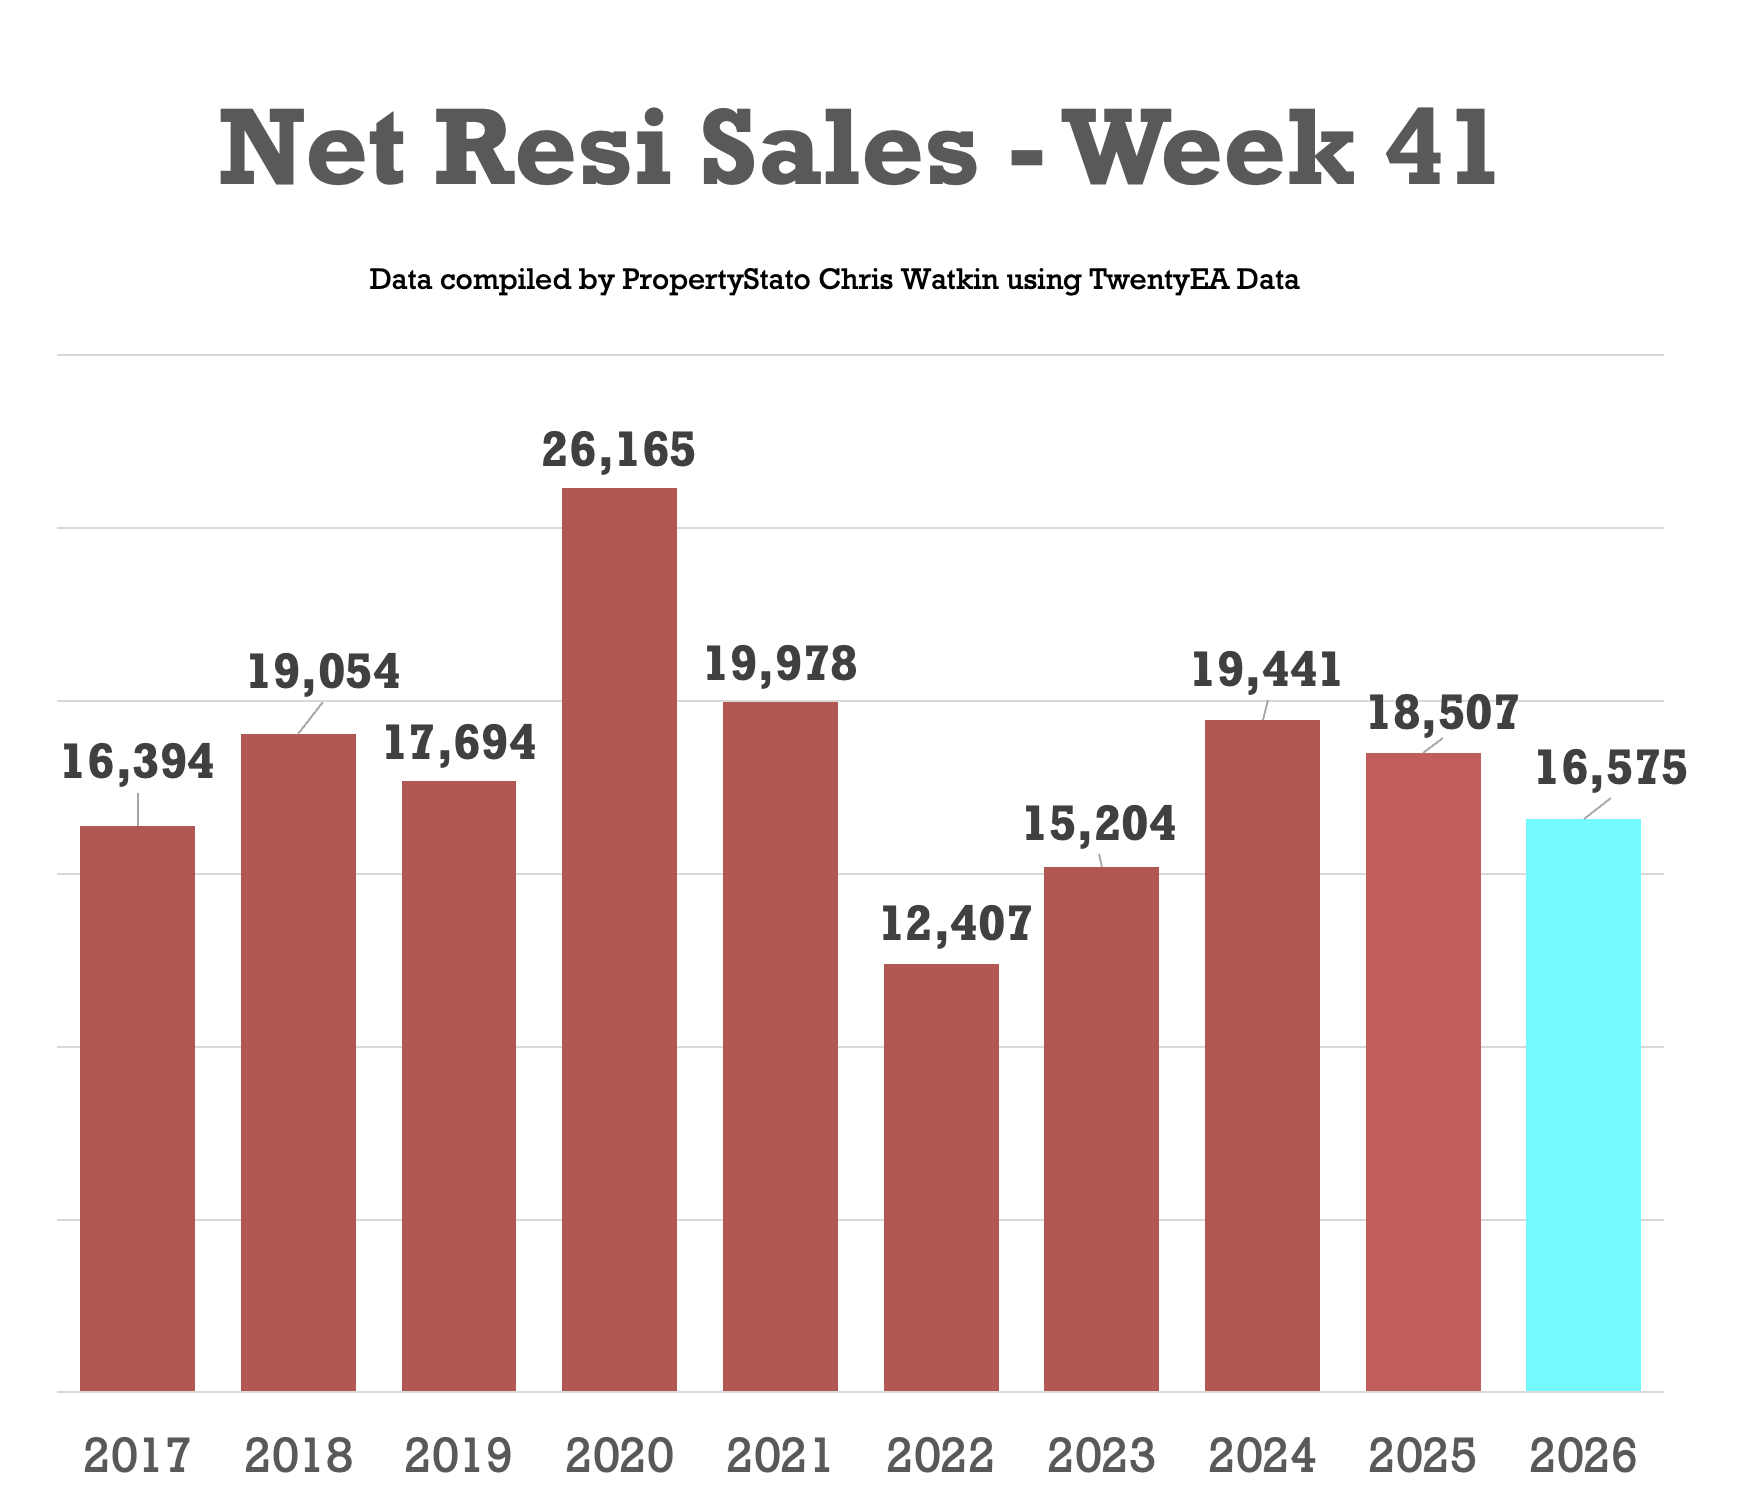
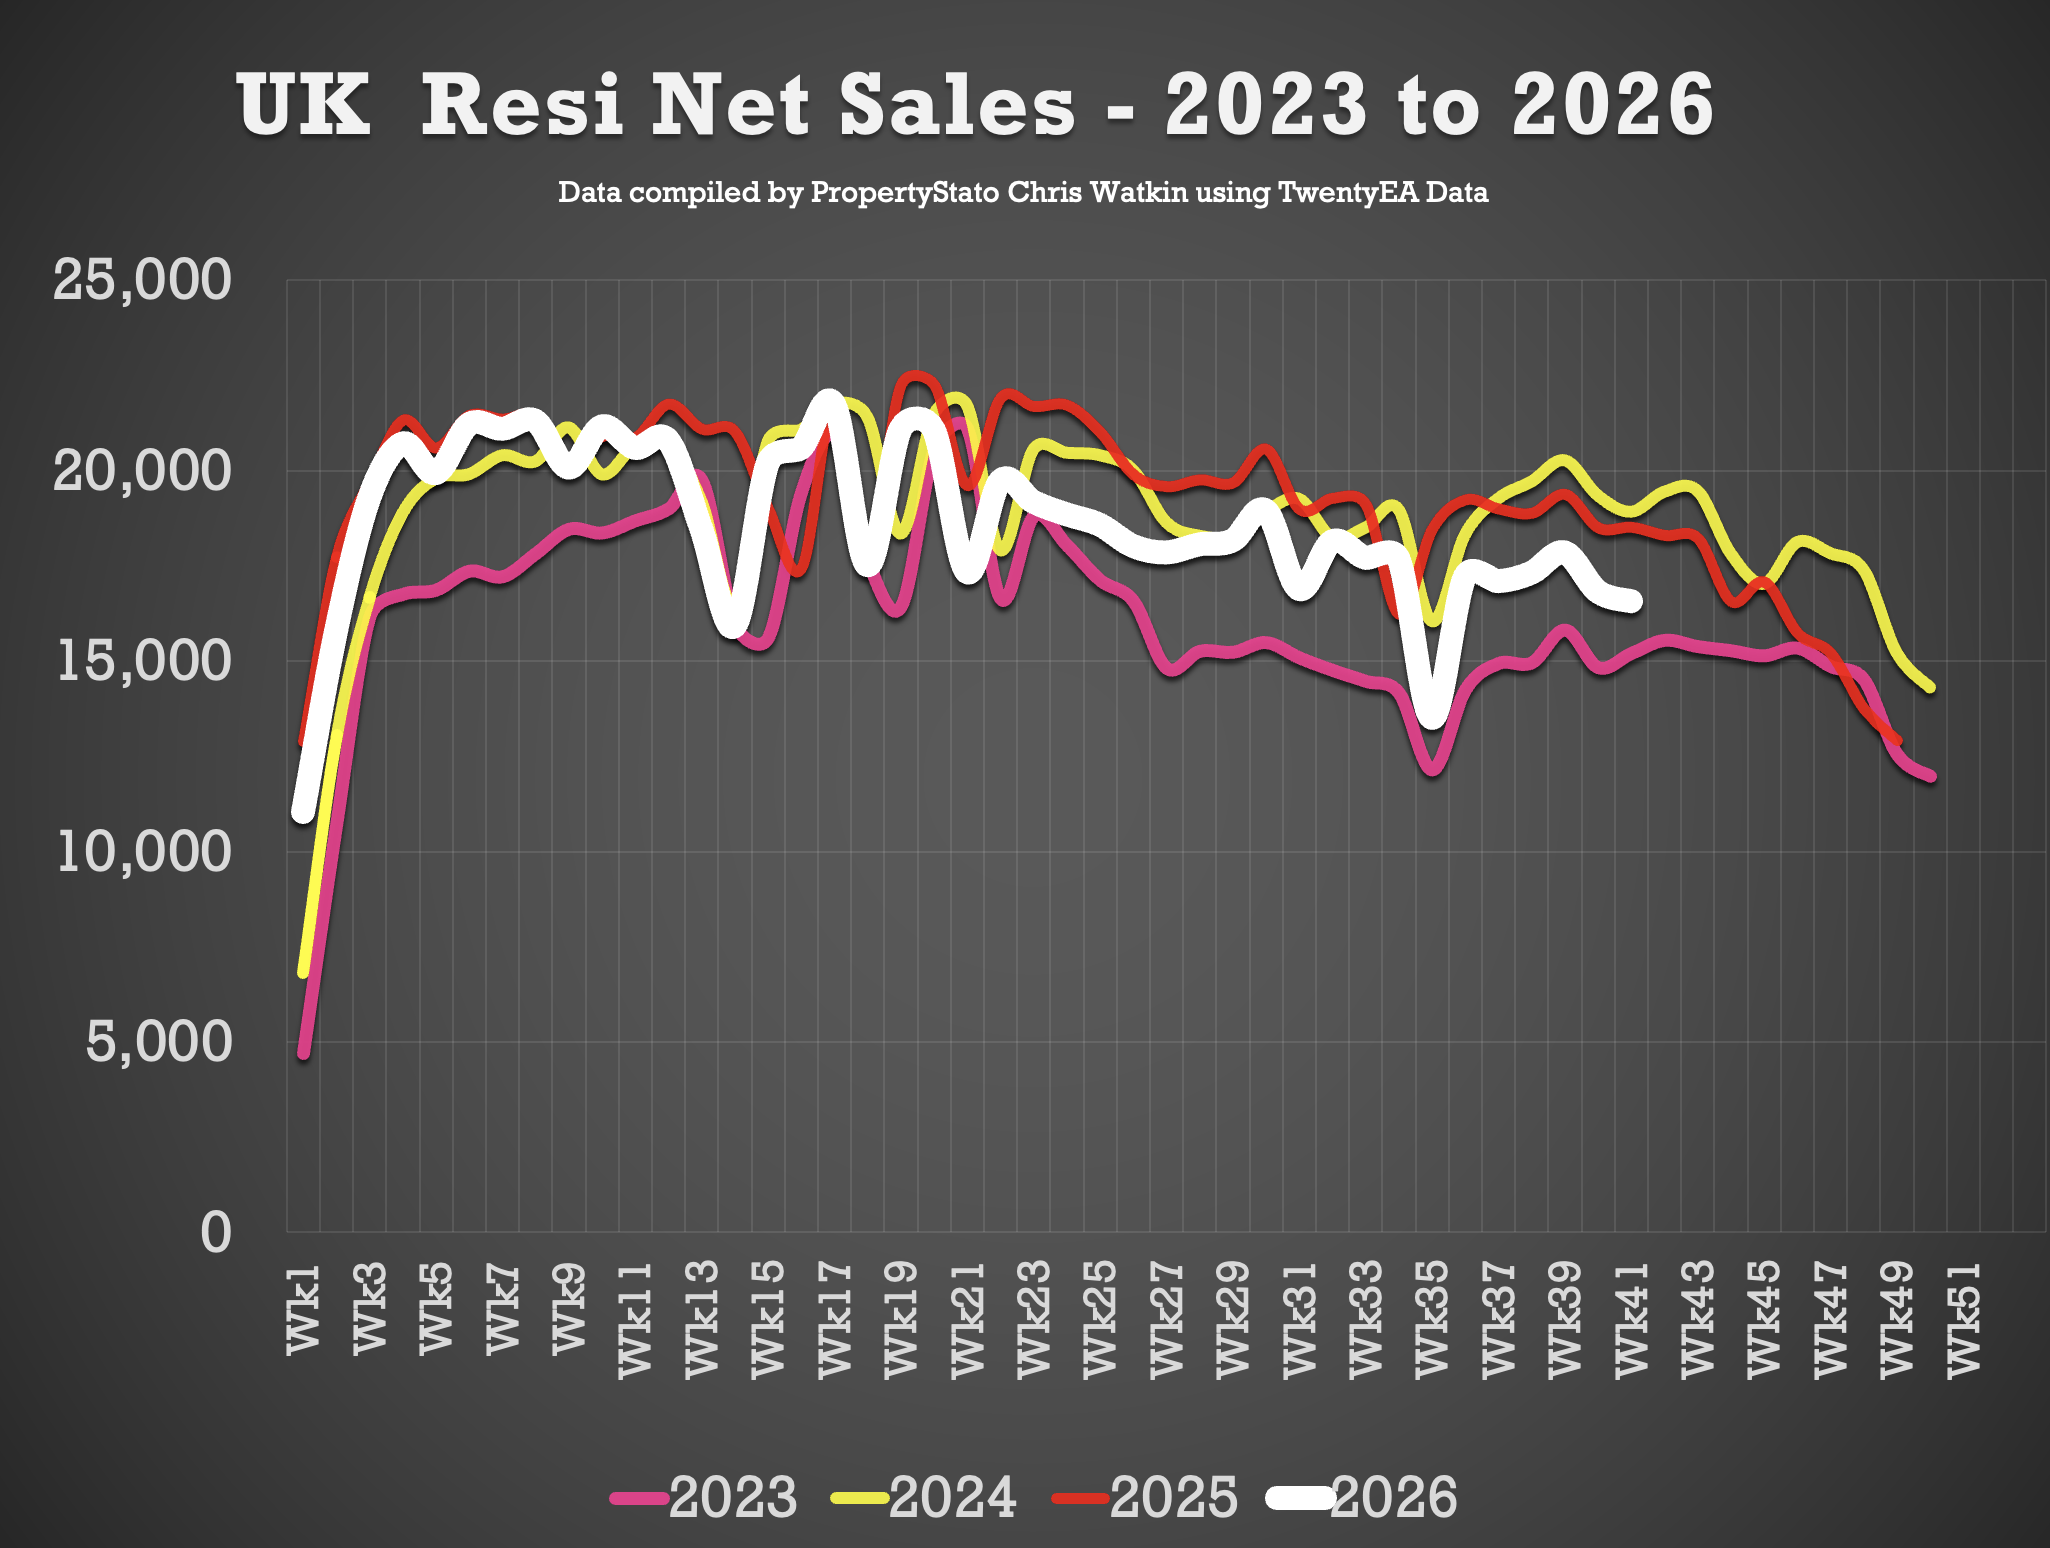
🟩 UK Net Resi Sales YTD
(Net Sales being Gross Sales less Sale Fall Thrus).
Week 41
16.6k Net Sales (16.8k last week)
10 year Week 41 average: 18.1k.
Weekly average for 2026: 18.6k.
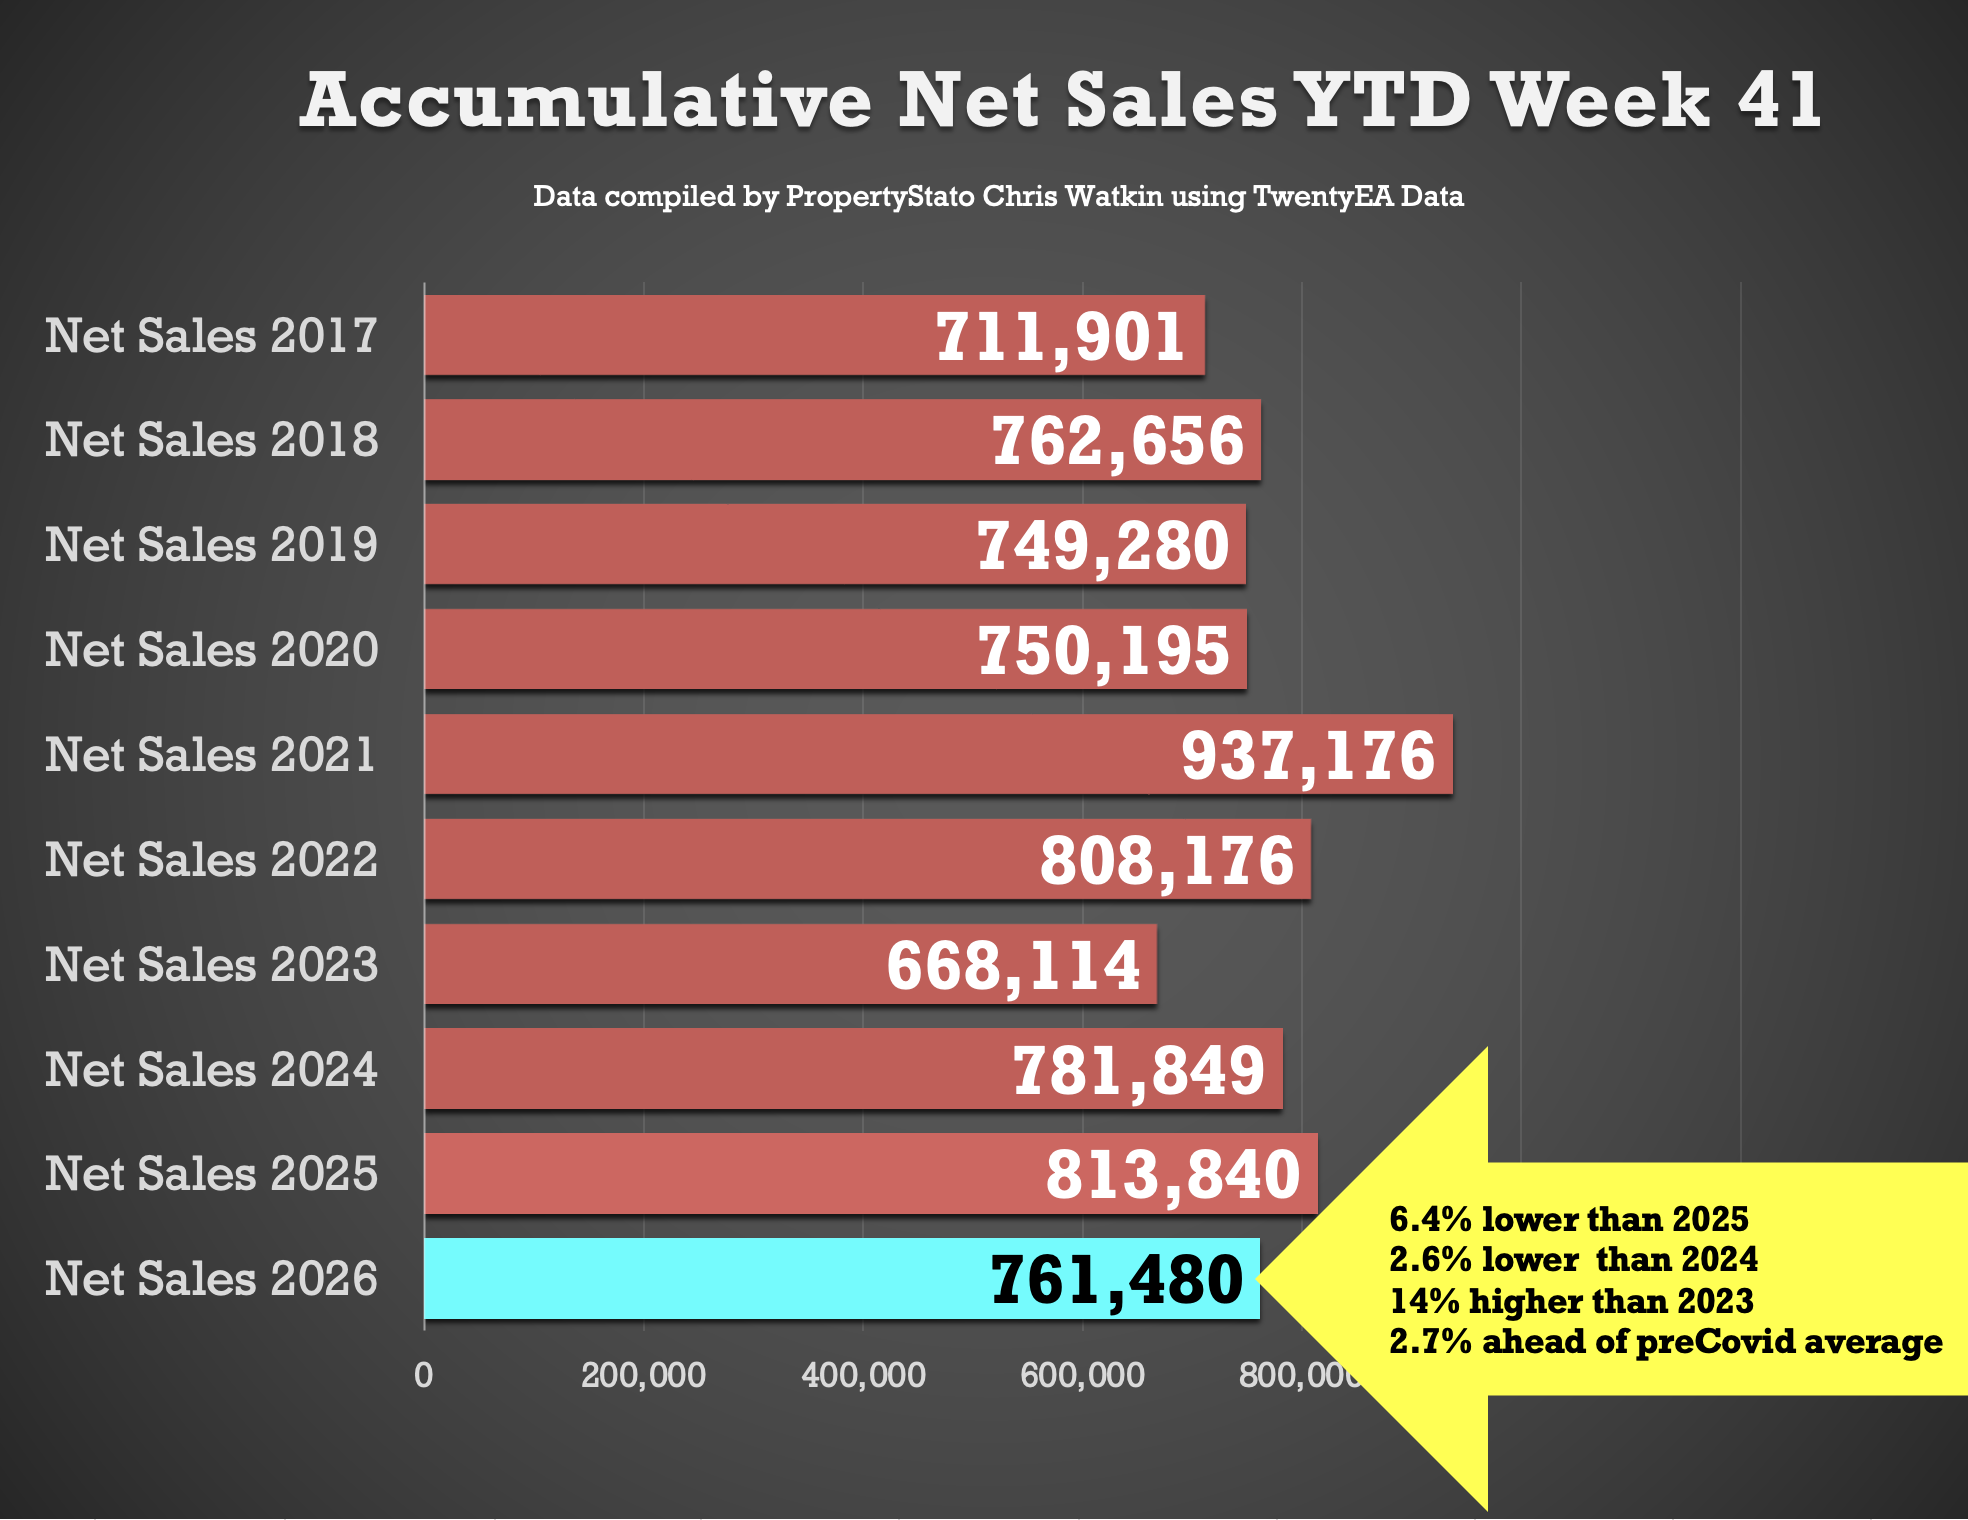
Year to Date
761k UK net home sales YTD, which is …
6.4% lower than 2025 (814k),
2.6% lower than 2024 (782k),
14% ahead of 2023 (668k)
2.7% above the 2017/18/19 average 741k).
🟩 Exchanges & Withdrawals
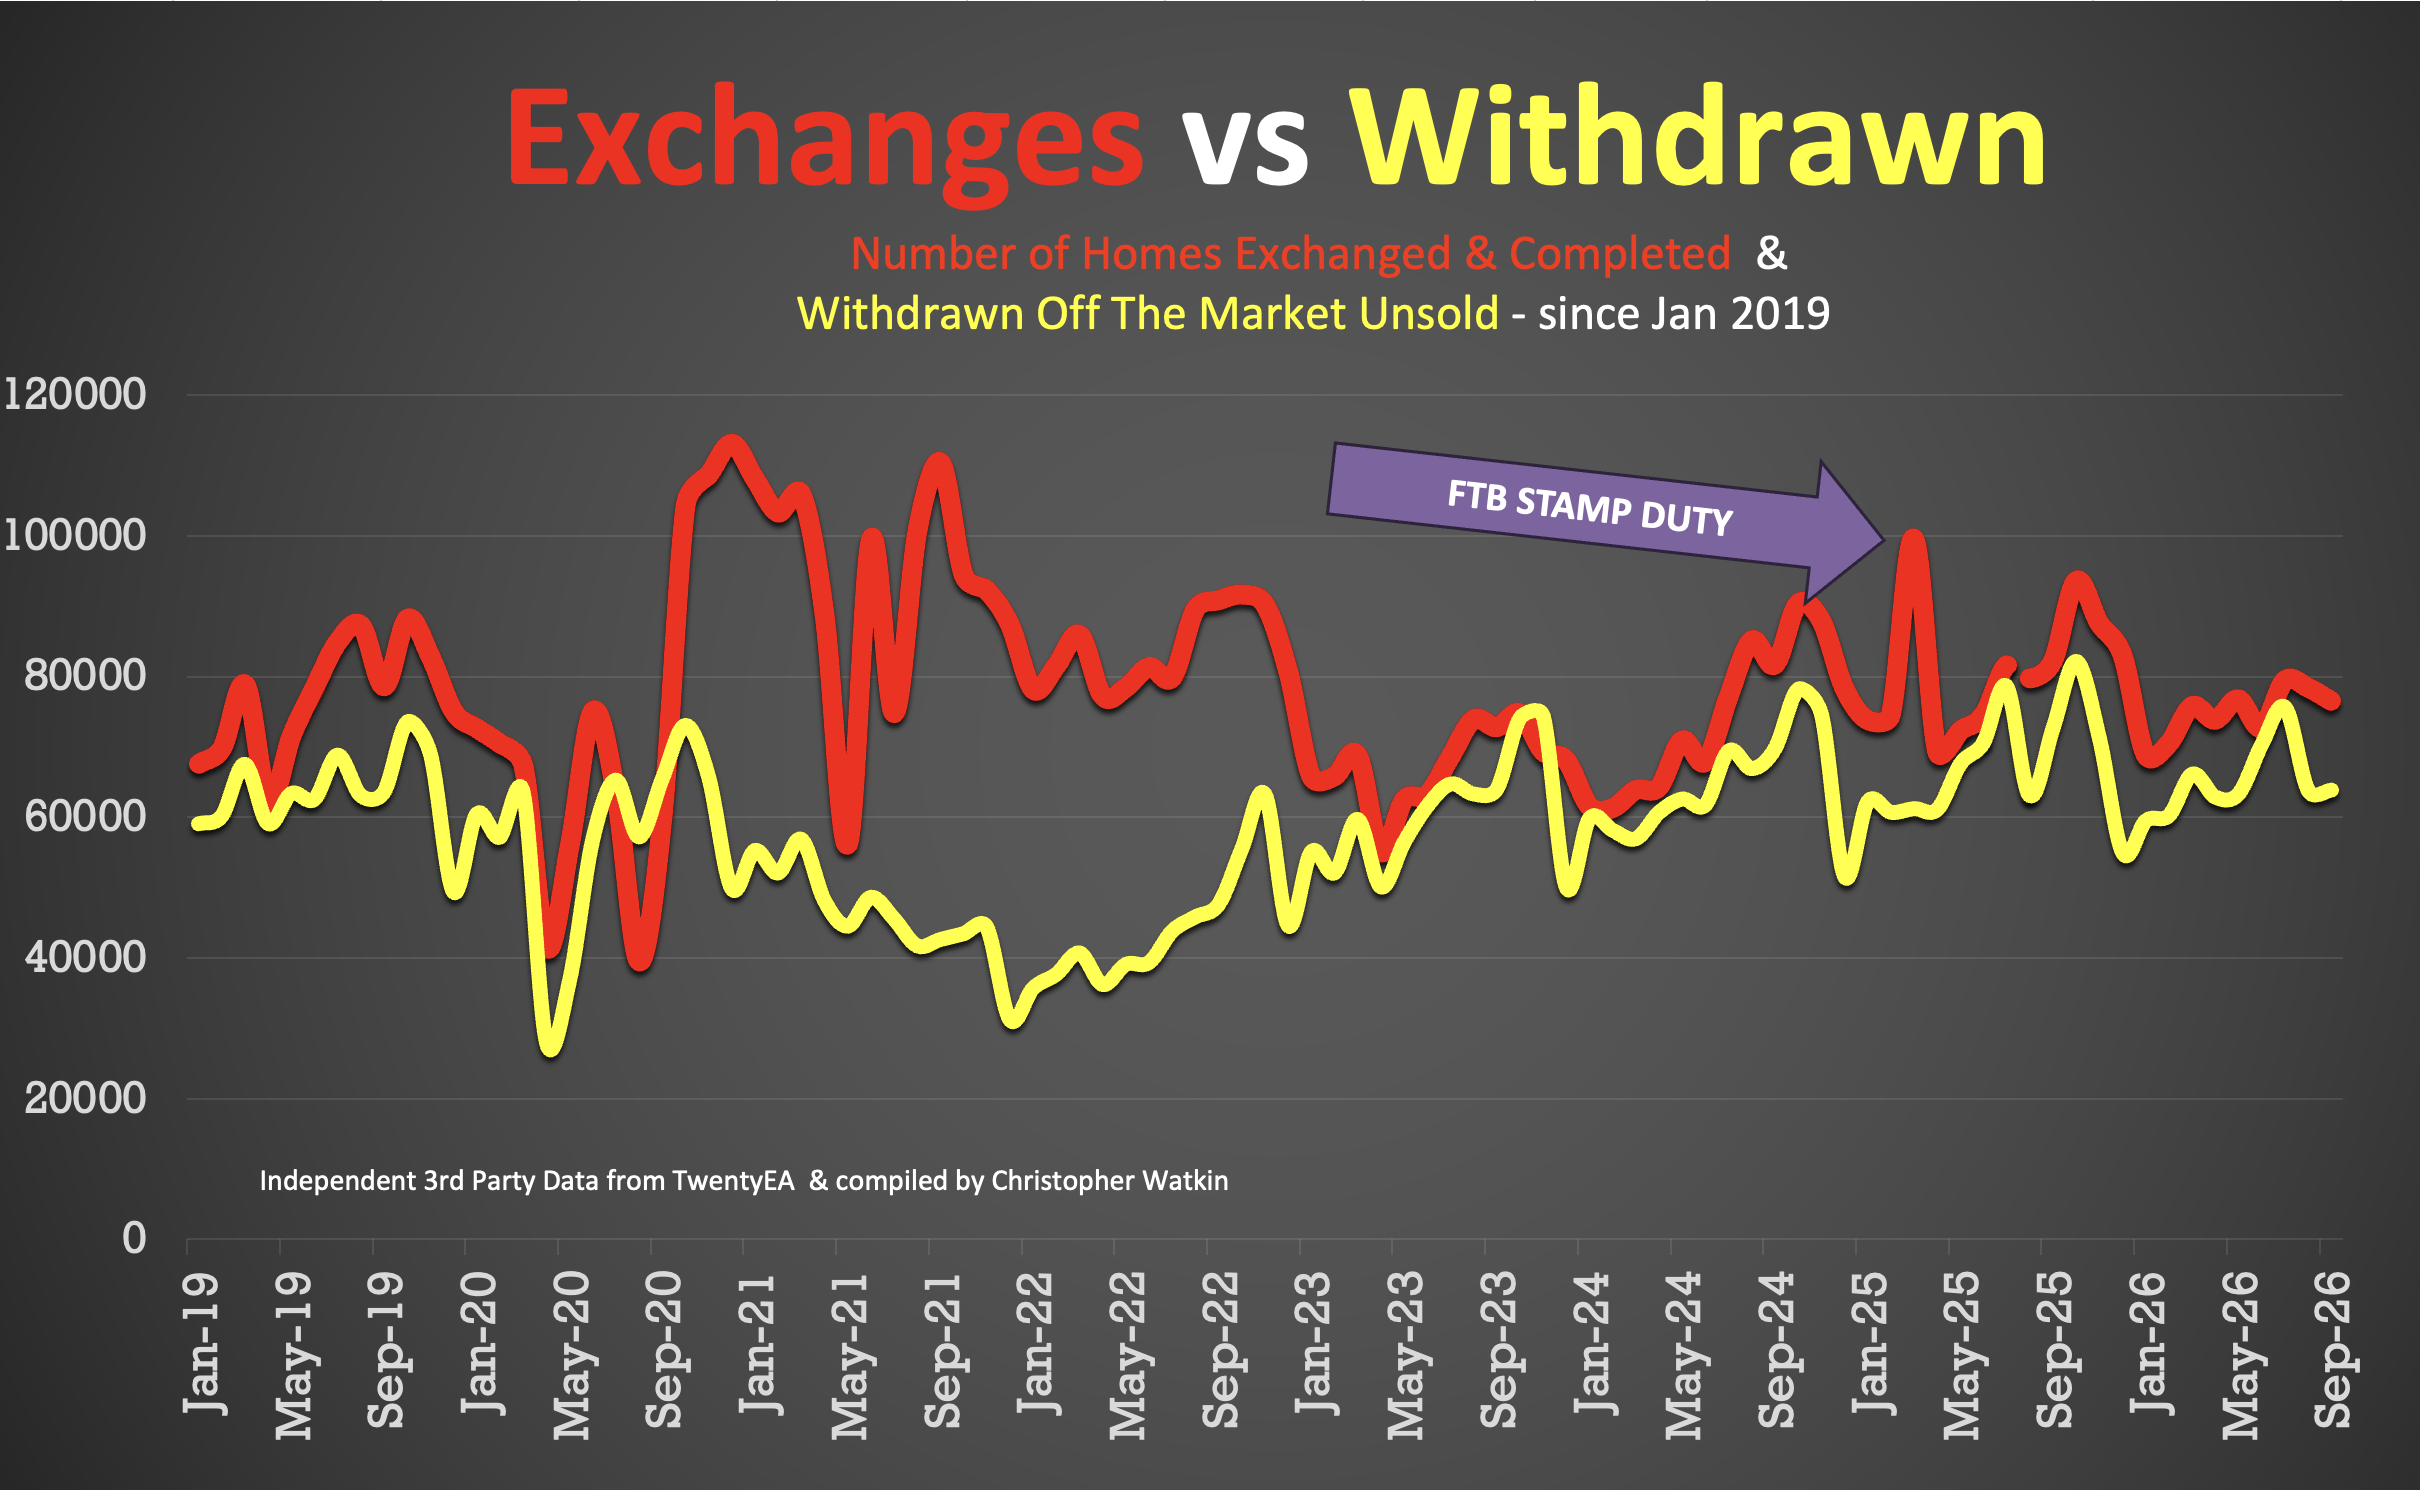
• 86.8k Exchanges in Sept 2026
• 73.8k Withdrawals in Sept 2026
(Note these numbers will change as more exchanges/ withdrawals from September come in during the first few weeks of October)
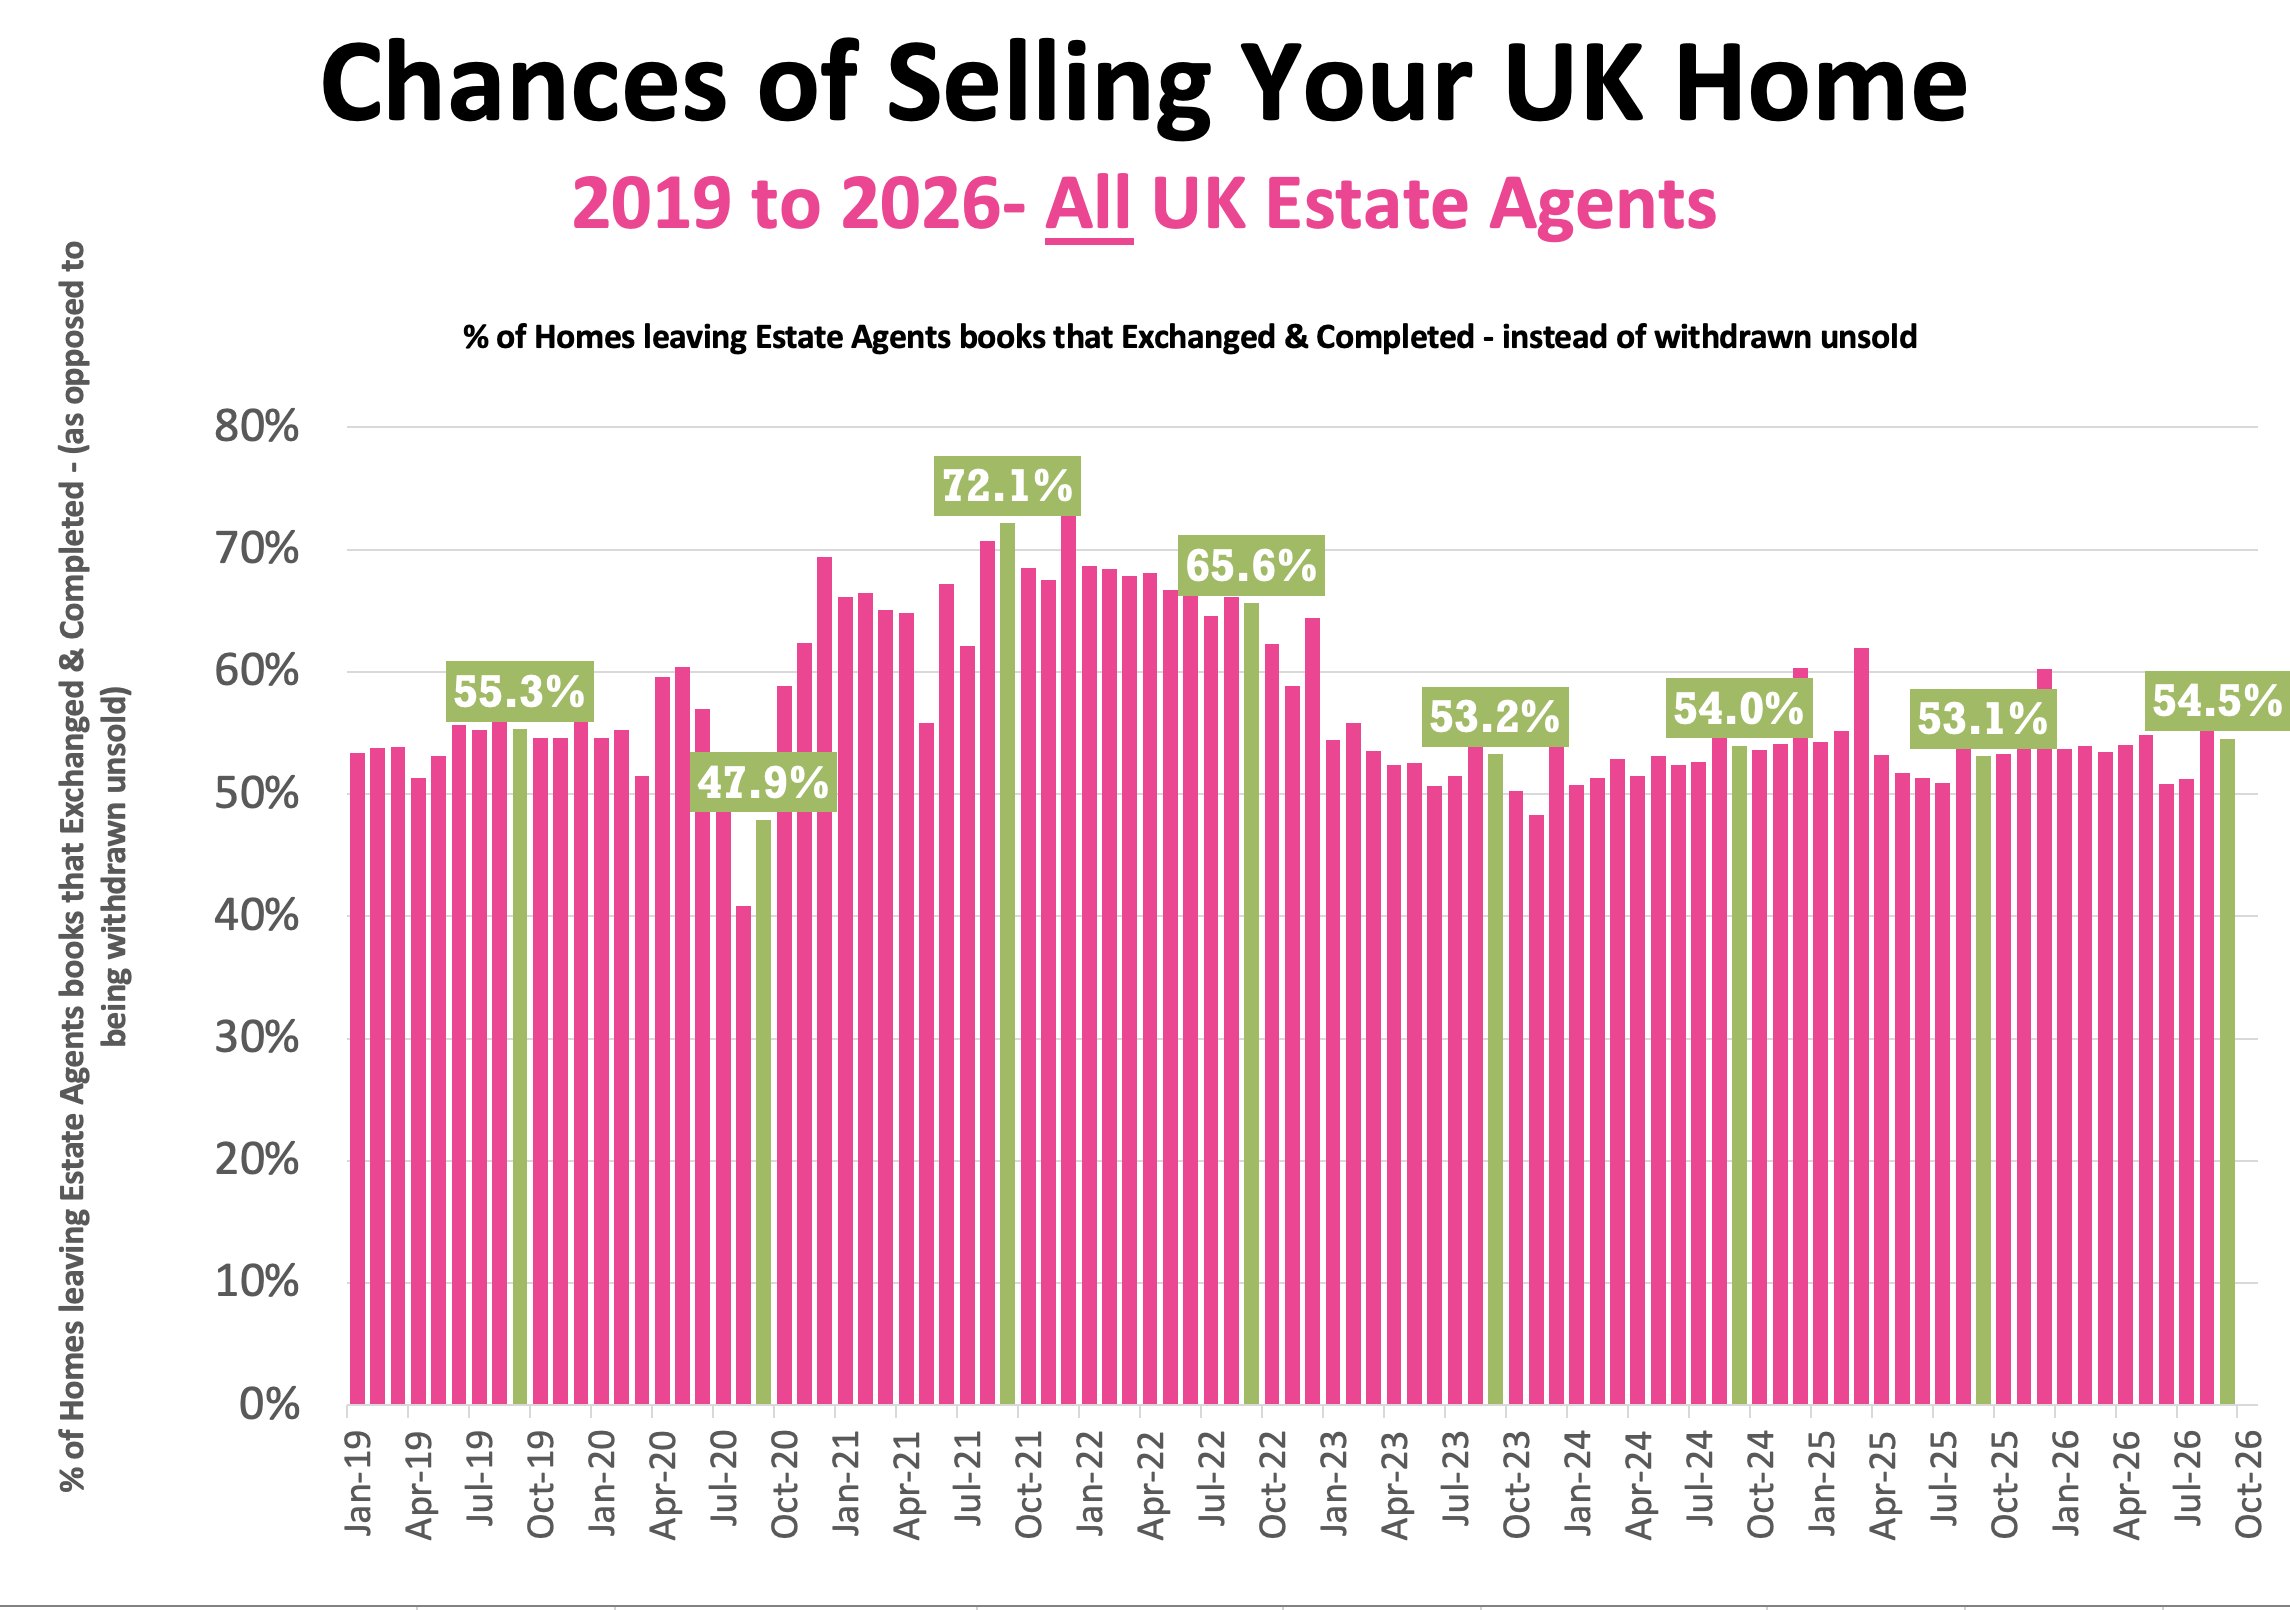
• Therefore, in September 2026, just 54% of homes that left agents’ books exchanged & completed in September (the rest – 46% withdrew, unsold)
• 57.6% is the 7 year average exchange to listings ratio (which includes the crazy years post lockdown 18 months).
Additional info …
🟥 Price Reductions
• 22.4k reductions this week on 764k UK homes for sale
• 14.7% of UK homes for sale were reduced in Sept (down from 11.1% in August)
• 2026 YTD average 13%, versus the 6 year long term average of 10.9%.
🟥 Price Difference between Asking Price of Listings & Asking Price of those Homes that go Sold stc
• Week 41 – 14.2% difference (long term 10 year average is 16% to 17%). (£418k ave Listing Ave Asking price vs £366k Sale Agreed ave Asking price)
🟥 Sell-Through Rate
• 14.7% of homes on agents’ books went SSTC in September ’26 (compared to 13.3% in August, 14.2% in July ’26 & 13.8% in June ’26).
• Pre-Covid average: 15.5%.
🟥 Sale Fall-Thrus
• Week 41 Fall-thru rate 26%
• Decade average: 24.5%
• 5.2% of homes sold STC fell thru in September 2026. Interesting when compared with the 2026 YTD average of 5.1% and 2025 average of 5.3% and the 10 year average of 5.7%.
🟥 Stock Levels
• 764k homes on the market on the 1st of October ’26 (752k on Oct 25, 722k on Oct 24, 662 Oct 23)
🟥 UK Rental Data
• Average Rent in Wk 41 – £1,831 pcm
• Average Rent in MTD October 2026 – £1,772 pcm
• Average Rent in October 2025 – £1,880 pcm (NB this is £108 higher than this year’s average … this is because student rentals in some Uni Cities start at the end of Oct and that will increase the overall for October 2025 by around £50/£60 per month
• Average Rent in October 2021 – £1,432 pcm
• Average Rent in YTD 2026 – £1,763 pcm
• 299k UK Rental Stock available to rent on 1st Oct 26 (295k on 1st Sept 2025)
• New Rental Properties coming onto the market in Sept 2026 – 127k (123k in Sept 2025 & 101k in Sept 2022)
🟥 House Prices (£/sq.ft)
• Sept ’26 agreed sales averaged £338.98 per sq.ft. 0.2% higher than 12 months ago (£338.90) and 13.7% than 5 years ago (£298.25).
The £/sqft at sale agreed matches the HM Land Registry Index with a 98% accuracy, 5 months in advance. That is why it is so important.
🟥 Local Focus this week in the Show
Burnley.

Comments (2)
Thank you Robert. There is certianly plenty here I agree with you. Agents inherit unrealistic expectatons, markets move & good agnets have difficult conversations every day.
But inheriting a vendor’s expectations & endorsing them are two different things.
“The instruction may go to someone who matches the estimate” gets to the heart of my argument.
Recommending a figure you cannot justify to secure a listing is a commerical decision. The pressure is understandable. The homeowner carries the consequences.
On ego, winning the instruction is the immediate prize. Being proved wrong comes later.
I agree this crosses every business model. The name above the door does not determine the quality of the advice.
Nor does a reduction automatically prove overvaluation. What matters is whether the original recommendation reflected the evidence available then.
Healthy sales agreed figures & weaker annual volumes can indeed my friend coexist. If I have given insufficient weight to that distinction, that is a fair challenge.
However, a five month lead over Land Registry does not mean every valuation tool is five months behind. It makes current local evidence and an agent’s judgemnt even more valuable.
Good agents deserve credit for navigating difficult markets. They also deserve an EA industry where honest advice is valued more than whichever number wins the listing.
This being a B2B platform makes that conversation relevant imho
Getting the listing matters. Getting the homeowner moved matters way way more.
Thank you for your comment
Chris, I have read this argument many times now, and I think the conclusion deserves a challenge.
This is a B2B platform and its audience is agents. When the message week after week is that agents overvalue, it can land badly with people who sit in front of vendors every day and live with the consequences.
It is a view I see from a number of commentators, not only here. Overvaluation is ego. Overvaluation is the corporates. The independents and the self-employed are getting it right. I do not think the evidence supports that.
On ego, an egotist wants to be right, and above all does not want to be seen to be wrong. A price reduction is the most public admission of being wrong an agent can make. It is hard to see ego choosing that.
On the corporates, I can show listings in [town], the same town used in your social media pieces, where independent agents have seen the market move away from them in exactly the same way. The market does not check the name above the door before it moves.
For much of this year, the message was that the market was strong. Agents on the ground were saying transaction volumes were down, but sales agreed looked healthy, so that view did not get much airtime. Your figures now show sales 7.5% down on last year, with stock at 764,000. The agents in the field saw it early.
Your figures also point to what I think is the real cause. You say the £/sq ft at sale agreed predicts the Land Registry index five months ahead. That is a five-month lag in the official record. AVMs and portal estimates are built on that record, so vendors arrive with expectations set by a market that has already moved.
In a falling market, the agent does not create that gap. The agent inherits it. Value at today’s level and the instruction may go to someone who matches the estimate. Match the estimate and the reduction follows. The rise in reductions and withdrawals you report looks to me like agents walking vendors down from stale data. That is navigation, not inflation.
The problem is data latency. The agents in the living room are the ones navigating it, and I think they deserve more credit for that than you give them.