Letting agents face renewed concerns over rental stock as tax changes threaten to push more landlords out of the market.
Some landlords could soon pay more in tax than they earn from their rental properties, according to Landlord Insurance UK.
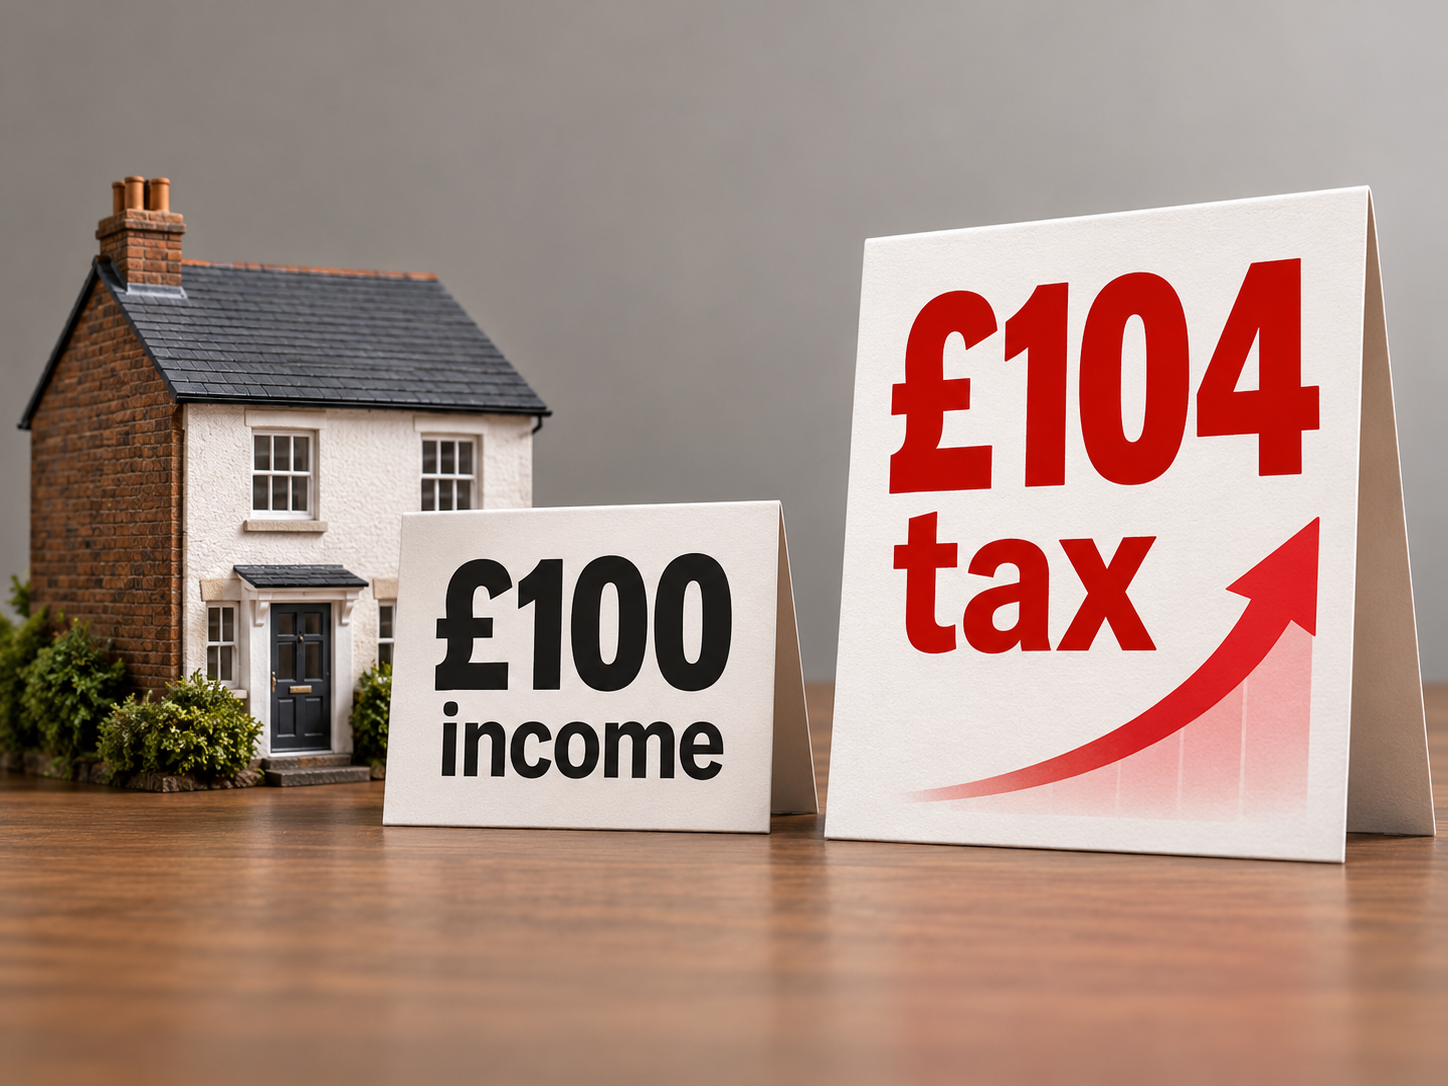
From April 2027, higher-rate landlords with large mortgages could pay £104 in tax for every £100 of actual profit.
For additional-rate taxpayers, that figure could reach £124.
The findings raise concerns about landlords selling up, leaving agents with fewer properties to manage.
Tax bills could exceed rental profits
Landlord Insurance UK examined the impact of higher property income tax rates and existing restrictions on mortgage interest relief.
Its calculations show how a higher-rate landlord could face a £5,200 tax bill on just £5,000 of actual profit.
The example assumes £20,000 in annual rental profit before mortgage interest.
Interest payments of £15,000 would leave the landlord with £5,000 before tax.
However, the resulting tax bill would exceed that profit by £200.
According to the firm, the same landlord would have paid £2,000 in tax in 2015-16.
That bill has since climbed to £5,000. It will rise again under the planned changes.
Two policies explain the increase.
Section 24 prevents individual landlords from deducting mortgage interest when calculating taxable rental income.
Instead, they receive a basic-rate tax reduction.
From April 2027, separate property income tax rates will apply. These will stand at 24%, 44% and 49%.
The mortgage interest tax reduction will also increase to 24%.
Landlord Insurance UK calculates that higher-rate landlords face tax bills exceeding their profits when interest consumes more than 73.7% of pre-interest earnings.
For additional-rate taxpayers, the threshold falls to 67.1%.
The examples assume other income has already used up the landlord’s lower tax bands.
Different rules apply to properties held through limited companies.
Buy-to-let investment under further pressure
Separate research suggests new buy-to-let purchases already struggle to generate profits across much of England and Wales.
Landlord Insurance UK examined the financial returns on typical properties in 316 council areas.
Its calculations assume a 75% interest-only mortgage at 5.34%.
The results suggest new purchases would fail to generate a profit before tax in 284 areas.
That represents almost nine in ten locations.
The analysis includes mortgage interest, letting agent fees, maintenance, insurance and average void periods.
In most areas, rental income would fail to cover those costs.
For letting agents, the concern extends beyond existing landlords selling up.
Weak investment returns could also discourage new landlords from entering the market.
However, the figures reflect a modelled purchase. Individual returns will depend on property prices, rents, borrowing and operating costs.
Further tax increases ahead
The latest changes add to mounting financial pressure on private landlords.
Landlord Insurance UK has identified 27 changes to landlord taxation and administrative requirements since 2015.
The firm says 21 increased tax liabilities or paperwork, while four reduced them.
HMRC estimates that the latest two-percentage-point tax increase will affect around 2.4 million landlords.
The measure could raise approximately £455m annually by 2031-32.
The Office for Budget Responsibility has also warned about the potential impact on tenants.
It says the government’s property tax measures could collectively contribute to a steady rise in rents.
‘Is it still worth carrying on?’
Chris Richards, director of Landlord Insurance UK, said: “A landlord with a typical buy-to-let mortgage is already handing their whole profit to HMRC. From next April, some will pay more in tax than the property earns them.
“For agents, that will be the conversation at every renewal: is it still worth carrying on?
“Nine in ten landlords are individuals and almost half own just one property, and they are the ones this hits.”
The findings suggest agents could face more difficult conversations with landlords about profitability and whether to retain their properties.
The impact will vary according to borrowing levels, rental income and ownership structures.
Nevertheless, higher tax bills could add to the pressure on landlords already questioning their future in the sector.